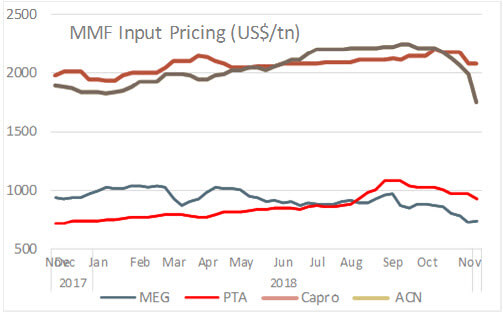
Polyester input: MEG
Mono ethylene glycol prices in Asia were softer opening the week but regained midweek only to fall at the weekend and posted a slight increase week-on-week amid weak sentiment and bearish macroeconomic conditions. The decline was, however, limited by slightly stabilising crude oil values and sporadic offers. Trades were limited, given the price gap between buying and selling indications. Meanwhile, inventories in east China decreased 2.7% to 658 kilo ton, on delayed cargo arrivals due to inclement weather. In Europe, spot prices were stable given the Rhine river logistical issues. In the US, contracts softened for the second month in a row as supply outweighed demand, setting the stage for a bearish end to the year. Seasonality, reduced exports and healthy production exerted downward pressure on spot markets. Demand from polyethylene terephthalate also decreased, with sentiment in the US and Latin American PET markets under pressure from more offers of competitively priced Asian material. Demand from the antifreeze and deicing sector picked up as colder weather set-in across the country.
MEG spot benchmark inched up US$3 week-on-week, despite rising US$10 midweek, with CFR China at US$675-680 a ton and CFR South East Asia flat at US$700 a ton. Bids for December shipments were at US$675 a ton CFR China Main Port against offers at US$685-688 a ton CFR CMP. In Europe, bulk prices were at Euro745-760 a ton CIF NEW and truck prices at Euro820-840 ton FCA NWE. In the US, November contracts were assessed at a decrease of US cents 4, pegged prices in the range of US cents 36.5-42.5 per pound FOB. Domestic spot prices were quoted in the mid-US cents 30s per pound (US$661 a ton) for barge material and at upper-US cents 30s per pound for rail/truck material.
Polyester input: PTA
Purified terephthalic acid markets were apparent poised to set up a bottom at the moment in Asia unless there are more unfavorable factors in macroeconomic market. However, a change on market trends will not appear until some substantial improvement emerges in demand. In China, plants have been operating at reduced rates due to weaker margins. In October-November, PTA production loss due to lower operation was estimated at 903,000 ton. European markets were calm with no change in sentiment and players awaited Rhine river logistic constraints to resolve soon. In the US, purified terephthalic acid demand was weak because of seasonal downturn and weak margins.
Asian PTA markers the CFR China edged down US$1 on the week to US$839-841 a ton while offers from Taiwan/Korea was flat at US$850-880 a ton. In China, offers for bonded goods were cut to US$840-895 a ton and discussions for nearby-month cargoes were at US$840-860 a ton. Yisheng Petrochemical’s daily prices fell to US$895 a ton while that of Hengli Petrochemical’s fell to US$840 a ton. In Europe, the November PTA contract price were in the range of Euro837-871 ton FD NWE. In the US, October prices were assessed at US cents 60.10 per pound DEL USG.
Caprolactam
Caprolactam spot and contract markets trended down across Asia and Europe this week. In Asia, prices plunged amid thin demand as mainstream values for liquid and flake materials in China declined sharply while they were soft in FE and SE region. Trading was insipid as downstream buying was on need-basis amid sidelined stance. Sinopec settled its November contract price lower than October due to falling feedstock prices and ample availability. Taiwan’s CPDC also settled its December contract price lower November amid falling upstream phenol values and weak downstream demand in a warm winter. In Europe, caprolactam November contracts settled at varying decreases on the back of a drop in the monthly price for feedstock benzene. There were firm negotiations in nylon 6 market for lower prices. Earlier there were attempts from producers to maintain healthier margins, but pressure in nylon market resulted in some decreases.
Asian caprolactam prices declined US$30-50 on the week, with SE and FE Asia markers at US$1,950-2,020 a ton. In China, spot prices for liquid goods plunged to 13,300-13,800 yuan a ton (US$1,920-1,990 a ton, down US$245) while flake goods fell to 13,800 yuan a ton (US$1,990 a ton, down US$320). Sinopec nominated December contract price at 15,300 a ton (US$2,205 a ton, down US$215) from November. Taiwan's CPDC settled its December contract price US$240 a ton lower from November at US$1,910 a ton CFR NE Asia. In Europe, November contract prices were assessed at decreases of Euro8 at the lower end and Euro15 at the higher end at Euro2,256-2402 a ton FD NWE.
Acrylic input: Acrylonitrile
Acrylonitrile markets extended the declining trend this week as demand continued to weaken while upstream propylene values continued their south-bound march. In Asia, spot prices fell on a stable‐to‐weak sentiment and offers were reduced, while suppliers rolled over offers in a quiet market. End‐users bought hand-to-mouth volume in expectation of stable sentiment. In China, both PetroChina Fushun and PetroChina Jilin Petchem lowered their settlement and offer price citing plunge in spot prices due to the soft demand from the acrylic fibre sector. In Europe, spot prices continued their slide for another week, pressured by ongoing falls in Asia while buyers have been calling for lower spot levels. In the US, November contracts fell as propylene contracts settled at a decrease. Despite lower contract settlements, inventories remained constrained amid expectations that demand will rebound in 2019.
The Asian acrylonitrile Far East CFR marker plunged US$100 to US$1,599-1,601 a ton while CFR China was down US$100 at US$1,550-1,650 a ton. In China, self-lifting values at Lianyungang port lost US$70 at US$1,590-1,615 a ton. PetroChina Fushun Petrochemical lowered its November settlement price to 10,500 yuan a ton (US$1,511 a ton, down US$45), while PetroChina Jilin Petrochemical lowered its offer price to 12,000 Yuan a ton (US$1,730 a ton, down US$144). In Europe, spot prices collapsed US$172 to US$1,448-1,152 a ton CIF Mediterranean. In the US, spot export prices also fell US$100 to US$1,520-1,530 a ton FOB USG. November domestic contracts also decreased to US cents 69.76-73.76 per pound (US$1,538-1,626 a ton) DEL USG.