Polyester input: MEG
Mono ethylene glycol prices trended lower in Asian markets this week as downstream polyester sales remained slow after the Chinese New Year. There was also a downward pressure on prompt arrival cargoes and domestic cargoes in China due to downstream buying had not begun after the holiday. Downstream were still recovering and may only resume normal operations around end February. Meanwhile, concerns over a slowdown in Chinese economy also dampened sentiment. Inventories along east China increased 27% to 1.14 million tons. Meanwhile, MEGlobal nominated its March Asian Contract Price higher from February. No report or update was available from European US markets this week hence prices are notionally rolled over.
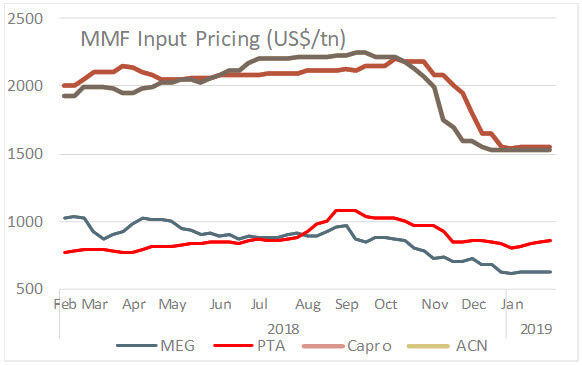
Asian spot benchmark fell US$10-12 on the week, with CFR China at US$608-613 a ton and CFR South East Asia to US$620-625 a ton. MEGlobal nominated its March contract price at US$830 a ton CFR Asia, US$20 higher from its February nomination. In Europe, truck prices were in the range of Euro640-670 a ton FCA NWE while fibre grade was traded at Euro618 a ton CFR. February contracts were agreed at Euro760 a ton FD NWE, down Euro30 from January. In the US, January contracts were assessed at US cents 29.5-35.5 per pound FOB. Initial February price were down US cents 3-5 per pound announced separately.
Polyester input: PTA
The purified terephthalic acid price movement was mixed this week, with benchmark China spot rising while Korea/Taiwan markers edged down. In China, the futures market also dropped in smaller range owing to the news about plant maintenance. Offers for PTA bonded goods were down while cash-based offers from Yisheng Petrochemical and Hengli Petrochemical maintained stable. From a fundamental point of view, there is no unfavorable factor for the market, but lacks momentum to go up in the short-term. Thus, the market is expected to resist a price drop and may fluctuate widely on the whole. In Europe, the contract for February hiked, moving alongside February paraxylene. The downstream PET market attributed the upward pressure to rising spot prices in Asia.
Asian PTA marker, the CFR China, gained US$8 on the week to US$855-857 a ton while offers from Taiwan/Korea were down US$5 at US$860-870 a ton. In China, offers for bonded goods were around US$860-880 a ton and the discussion for nearby-month cargoes was relatively weak. Yisheng Petrochemical’s daily prices were flat at US$880 a ton and that of Hengli Petrochemical’s at US$860 a ton. In Europe, February contract price was up Euro30 to Euro770-804 a ton FD NWE. In the US, January contracts were at US cents 49.71 per pound (US$1,096 a ton).
Nylon input: Caprolactam
Caprolactam suppliers in China hiked offers on modest downstream demand and increasing cyclohexanone cost. Mainstream values for liquid and flake materials were raised 3-8% week-on-week, while Fibrant raised its February contract nomination by more than 2% for liquid goods. Japan's Ube Industries settled its February contract higher citing that the increase comes amid stronger demand for downstream nylon chips after the Lunar New Year holidays. Meanwhile, the SE and FE markets remained unchanged on the week. In Europe, caprolactam February contract discussions remained inconclusive as spot remained well supplied, despite earlier concerns in upstream cyclohexane market. The marker remained balanced as demand remained seasonally low.
Asian caprolactam prices were steady on the week, with SE and FE Asia markers at US$1,550-1,600 a ton. In China, spot prices for liquid goods jumped to 13,100-13,500 Yuan a ton (US$1,940-1,995 a ton, up US$45) while offers for flake goods hiked to 14,000-14,500 Yuan a ton (US$2,070-2,145 a ton, up US$130). Japan's Ube Industries settled its February caprolactam contract price at US$1,635 a ton CFR Northeast Asia, up US$15 from January. Fibrant raised its February nomination for liquid goods to 13,700 Yuan a ton (US$2,025 a ton, up US$30). In Europe, January contracts settled at Euro2,116-2,235 a ton FD NWE.
Acrylic input: Acrylonitrile
Acrylonitrile prices jumped on an upward trajectory across regions this week due to planned and unplanned shutdown and force majeure. In Asia, offers ran up as the market atmosphere warmed up after the holiday, with sellers keen to hike offers, which were taken cautiously by downstream buyers. PetroChina Jilin Petrochemical raised its February offer price as domestic spot prices gained slightly after the Lunar New Year on the back of healthy downstream demand. In Europe, INEOS Nitriles declared force majeure at its Seal Sands acrylonitrile plant in UK, ahead of a planned 35-day turnaround scheduled in early May. The declaration coincides with an operational issue that caused INEOS to shut its plant in Texas, US, this week. The production asserted upward pressure on prices following the end of the New Year holiday, after which demand for typically increases in Asia. The outages also coincide with an ongoing turnaround at Formosa's plant in Mailiao, Taiwan, that began earlier in the week. In the US, unexpected supply disruptions added upward pressure on export prices. The combination of tight supply and steady increase in demand is likely to push prices higher in the short-term.
Asian acrylonitrile Far East CFR markers were up US$30 on the week at US$1,559-1,561 a ton, while CFR China rolled over at US$1,400-1,450 a ton. In China, self-lifting values at Lianyungang port were up US$15 at US$1,805-1,850 a ton. PetroChina Jilin increased its February offer to 11,700 Yuan a ton (US$1,730 a ton, up US$15). In Europe, prices jumped US$70 to US$1,288-1,292 a ton CIF Mediterranean. In the US, spot export prices surged US$105 to US$1,445-1,455 a ton FOB in the US Gulf.