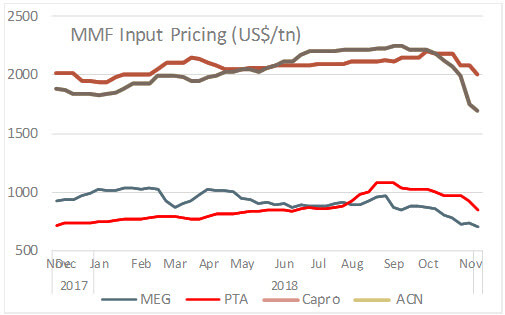
Polyester input: MEG
Monoethylene glycol markets in Asia fluctuated in weakness, and transactions were moderate this week. However, the week closed with spot prices up, as inventories along east China decreased 5% to 623 kilo ton. From levels in early November, inventories were down 10%. December deliveries were flat from spot numbers, while January deliveries were lower than spot numbers. In Europe, the monoethylene glycol market braced further declines after the steep triple-digit fall in the December ethylene contract price. Although spot prices have not reached bottom and saw extended declines during the week despite some rebound seen in Asian market earlier in the week. Players were finding it hard to see an end to falling prices and sentiment remains bearish. Meanwhile, December contracts remained inconclusive despite negotiations had gathered pace. In the US, monoethylene glycol markets were calm and both contract and domestic spot numbers rolled over.
MEG spot benchmark gained US$30 week-on-week, with CFR China at US$705-710 a ton and CFR South East Asia at US$730 a ton. In China, offers for nearby-month cargoes were at about USS725 a ton and bids at US$720 a ton. In Europe, bulk spot prices were down Euro35 at the low end and Euro25 at the high, pegging prices at Euro685-710 a ton CIF NWE. Spot prices in the truck sector were down Euro15 at both ends, bringing prices to Euro780-805 a ton FCA NWE. Fibre grade prices were heard up at Euro805 a ton FCA. In US, November contracts were assessed at US cents 36.5-42.5 per pound FOB while domestic spot prices were quoted in the mid-US cents 30s per pound (US$661 a ton) for barge material and at upper-US cents 30s per pound for rail/truck material.
Polyester input: PTA
Purified terephthalic acid markets in Asia reversed the weakening trend with favorable macroeconomic development and a sharp drop followed by a rebound on crude oil market. In China, the futures market rushed up with great momentum as paraxylene values increased sharply on the week. Offers for bonded goods and for nearby-month cargoes were also higher on the week. In Europe, purified terephthalic acid buyers were pushing back producers’ targets for higher conversion fees in 2019 because of bearish markets. For PTA, despite the restart of a plant in Portugal, the regions still needs to imports it traditionally from South Korea and to a degree Mexico. In the US, November purified terephthalic acid contracts declined tracking weaker contract for paraxylene. Meanwhile, supply eased as downstream consumption of polyethylene terephthalate declined due to excess supply in global market.
Asian PTA markers the CFR China gained US$11 on the week to US$850-852 a ton, while offers from Taiwan/Korea were up US$10 at US$860-900 a ton. In China, offers for bonded goods were at US$850-890 a ton and discussions for nearby-month cargoes were at US$860-870 a ton. Yisheng Petrochemical’s daily prices were at US$900 a ton while that of Hengli Petrochemical’s at US$850 a ton. In Europe, November PTA contract price were in the range of Euro837-871 ton FD NWE. In US, November contracts fell to US cents 54.40 per pound (US$1,199 a ton) DEL USG from US cents 60.10 per pound DEL USG for October.
Caprolactam
Caprolactam spot prices declined to a 17-month low this week in far-east and south-east Asian markets, due to weakness and thin demand from the downstream nylon sector amid falling benzene costs. Demand from the nylon sector weakened amid narrowing production margins, with prices expected to continue on a downtrend during December. However, buyers were hopeful for a Lunar New Year ‘miracle’, during which prices may pick up. In Europe, discussions for December caprolactam continued but could not make progress. Meanwhile, precursor cyclohexane contract price for December fell triple digits on the back of a drop in benzene monthly contract. In the US, the cyclohexane December contract price softened to its lowest since November 2016, following the third-consecutive decrease in the monthly benzene contract settlement.
Asian caprolactam prices plunged US$150-180 on the week with SE and FE Asia markers at US$1,800-1,850 a ton. In China, spot prices for liquid goods gained at 13,700-14,200 Yuan a ton (US$1,995-2,070 a ton, up US$80) while flake goods were flat at 14,000 Yuan a ton (US$2,040 a ton). Sinopec nominated December contract price at 14,500 a ton (US$2,110 a ton, down US$95) from previous nomination. In Europe, November contract prices were assessed at Euro2,256-2402 a ton FD NWE. The contract price for December cyclohexane settled down on the month at Euro707 a ton ex-works NWE. In the US, December cyclohexane settled at US cents 256 per gallon FOB US Gulf, down US cents 39 compared to the previous month.
Acrylic input: Acrylonitrile
Acrylonitrile markets in Asia continued to seek prices stability this week, with some rushing up and down and rolling over. In China, domestic spot values rose during the week, propped by upstream propylene collecting strength. Offers at port Lianyungang jumped sharply as suppliers reserved their offers to wait for clear signs of a rebound. Supply was steady while demand was on the uptick. Major producers raised their contract and spot offers citing recovery in acrylic fibre demand. ABS values also inched up. Market expect price to rise mildly in coming week due to the approaching year end. In Europe, acrylonitrile spot prices continued their nosedive for another week, falling even more steeply than their previous week’s fall. Softening feedstock and slower-than-expected demand have contributed to the downward price pressure. In the US, export offers rolled over after nine weeks of fall while domestic markets were stable.
Asian acrylonitrile Far East CFR marker rolled over at US$1,599-1,601 a ton, while CFR China was steady at US$1,550-1,650 a ton. In China, self-lifting values at Lianyungang port regained US$100 at US$1,690-1,705 a ton. Sinopec Anqing increased its contract and spot offers to 11,800 a ton ex-works (US$1,720 a ton, up US$29 while PetroChina Jilin raised its offers to 10,900 Yuan a ton (US$1,590 a ton, up US$29) ex-warehouse. Prices in India were corrected down US$35-50 at US$1,565-1,600 a ton CFR. In Europe, spot prices plunged further by US$180 to US$1,268-1,272 a ton CIF Mediterranean. In the US, spot export prices rolled over at US$1,520-1,530 a ton FOB USG.