Polyester input: MEG
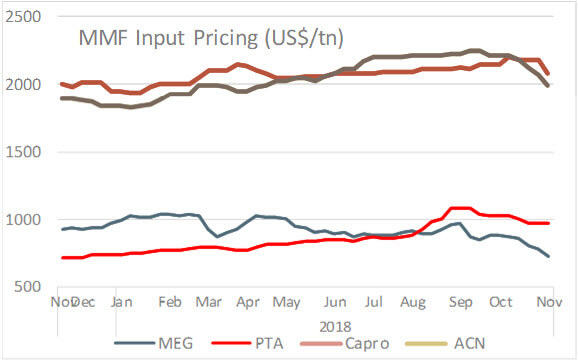
Mono ethylene glycol prices in Asia declined sharply due to weak market sentiment, dampened by recent losses in crude oil values and slow polyester sales. Major Chinese producer Sinopec also reduced its November settlement prices in east China, in line with the declining spot values. Meanwhile, inventories in east China increased 2.3% week-on-week to 676 kilo ton – which weighed on the spot markets. SABIC and Shell nominated their December contract prices at more than US$100 lower than November numbers. In Europe, November contract was fully confirmed at a drop compared to October following an initial November settlement, which emerged alongside the full confirmation of October contracts earlier in the week. Spot prices were on a downward trajectory, along with continued weakness in Asian market, as players often look at Asia for direction. In the US, contract prices remained unchanged for the moment while spot numbers rolled over.
MEG spot benchmark fell US$50 week-on-week with CFR China at US$672-677 a ton and CFR South East Asia down US$34 at US$700 a ton. SABIC and Shell have nominated their December Asia contract price more than US$100 below their November nominations. SABIC nominated at US$940 a ton CFR Asia, down US$140 from the month ago, while Shell nominated at US$900 a ton, down US$170 over the month. In Europe, bulk prices were at Euro745-760 a ton CIF NEW and truck prices at Euro820-840 ton FCA NWE. November contract was fully confirmed at Euro925 a ton, down Euro 74 compared to October, while October contract was fully confirmed at Euro 999 a ton, a decreased of Euro 13 from September. In the US, MEG contracts prices were stable at US cents 40.5-46.5 per pound FOB.
Polyester input: PTA
Purified terephthalic acid prices continued to downtrend in Asian markets due to weaker downstream demand. Prices declined close to 8% week-on-week. A weak global macroeconomic environment, coupled with slower sales in the downstream polyester markets curbed buying interest, and exerted a downward pressure on the raw material prices. Sales in the polyester sector in key China markets have resulted in a bearish market sentiment. According to reports, sales-to-output ratio in polyester sectors has trended below the 100% healthy level for many weeks and showed no signs of improvement. In Europe, purified terephathalic acid market was calm and quiet as Rhine river logistics continued to impact both upstream and downstream businesses.
Asian PTA markers the CFR China plunged US$70 on the week to US$840-842 a ton while offer from Taiwan/Korea fell to US$850-880 a ton. In China, offers for bonded goods were trimmed to US$870-820 a ton and discussions for nearby-month cargoes were still lower. Yisheng Petrochemical’s daily prices fell to US$910 a ton while that of Hengli Petrochemical’s fell to US$870 a ton. In Europe, November PTA contract price were in the range of Euro837-871 ton FD NWE. In US, October prices were assessed at US cents 60.10 per pound DEL USG.
Nylon input: Caprolactam
Caprolactam prices dipped in the Asian market following a sharp drop in feedstock benzene cost and long supply amid thin demand. Sinopec settled its November contract price sharply down from its nomination while Japan’s Sumitomo Chemical announced its November contract price lower than the previous month. Falling upstream values and bearish sentiment in downstream markets are expected to support its offer. Downstream demand was hard to improve since run rates of polymerization units are steady at 75% and inventory worth five days. Nylon yarn makers were also running steady at 79% with inventory of 20 days’ worth. With benzene market weakening, and caprolactam supply increasing, market participants appear cautious and prices are likely to drop further. In Europe, discussions for November caprolactam contracts were difficult, with an expected reduction in the monthly benzene contract adding to buyers' arguments for decreases.
Asian caprolactam prices declined US$50-80 on the week with SE and FE Asia markers at US$2,000-2,050 a ton. In China, spot prices for liquid goods fell to 15,000-16,000 Yuan a ton (US$2,165-2,210 a ton, down US$140) while flake goods fell to 16,000 Yuan a ton (US$2,310 a ton, down US$70). Sinopec settled November contract price at 16,300 a ton (US$2,350 a ton) while Fibrant nomination was at 17,300 Yuan a ton (US$2,495 a ton). Japan’s Sumitomo Chemical announced its November contract price at US$2,150 a ton CFR NE Asia, US$100 lower than the previous month. In Europe, October contract prices were settled in the range of Euro2,264-2,417 a ton FD NWE and cyclohexane November contract settled at Euro858 a ton ex-works.
Acrylic input: Acrylonitrile
Acrylonitrile prices in Asia declined for the fifth consecutive week as demand waned rapidly and most participants were taking a wait‐and‐see stance ahead of the announcement of monthly settlements, while upstream propylene continued to trend downwards. Major producers in China reduced their November prices sharply from their respective October levels. In Europe, acrylonitrile spot prices fell sharply for another week with pressure largely coming from persistent downtrend in Asian market. Meanwhile, November contract prices also fell on the month on the back of lower raw material costs and improving market balance. In US, spot export prices fell to its lowest level since mid-April amid falling prices in Asia and seasonal downturn in acrylic fibre and ABS demand. Snug supply continued to limit incentive for producers to sell material in spot market versus rebuilding inventories for 2019, when demand is expected to be stronger.
Asian acrylonitrile Far East CFR marker further plunged US$50 to US$1,699-1,701 a ton, while CFR China was flat at US$1,650-1,750 a ton. In China, self-lifting values at Lianyungang port however, lost US$40 to US$1,660-1,670 a ton. Sinopec Anqing Petro settled its November price at 11,600 Yuan a ton (US$1,674 a ton), 6,400 Yuan (US$923 ton) lower from October while PetroChina Jilin sharply decreased its prices by US$216.5 to 13,000 Yuan a ton (US$1,875 a ton) ex-warehouse. In Europe, spot prices declined US$28 to US$1,620-1,624 a ton CIF Mediterranean. Contract prices were agreed in the range of Euro2,160-2,228 a ton FD NWE. In the US, spot export prices pummeled US$50 to US$1,60-1,630 a ton FOB USG.