Polyester input: MEG
Mono ethylene glycol prices were seen firm in Asian markets amid higher crude oil prices and expectations of improved downstream polyester demand after the Chinese New Year holidays. In Europe, the February contract was confirmed at a decrease from January as ethylene contract rolled over. Nevertheless, there were signs of spot price dipping slowly after weeks of extended pressure. Players were waiting to see how the market in Asia develops after the Lunar New Year. In the US, ethylene glycol buying interest was low, with large de-stocking taking place. This emerges when players are monitoring upcoming new capacity and US-China trade discussions. If US-China strike a deal to end the trade war by 1 March, the upward pressure could come from increased exports tapping into domestic supply.
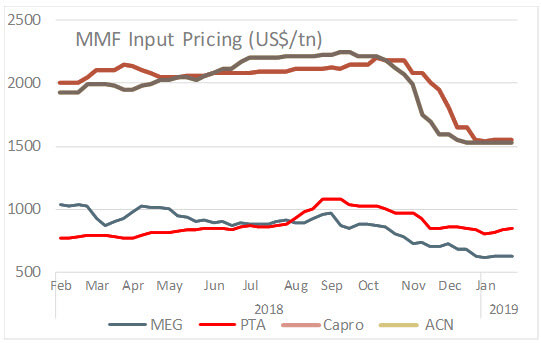
Asian spot benchmark rolled over on the week, with CFR China at US$620-625 a ton, while CFR South East Asia was flat at US$630-635 a ton. In China, after the week-long holidays, Futures on DEC opened at 5,295 Yuan a ton (US$785 a ton), a rollover from the settlement price of the previous trading day. In Europe, truck prices were in the range of Euro640-670 a ton FCA NEW while fibre grade was traded at Euro618 a ton CFR. February contracts were agreed at Euro760 a ton FD NWE, down Euro30 from January. In the US, January contracts were assessed at US cents 29.5-35.5 per pound FOB. Initial February price were down US cents 3-5 per pound announced separately.
Polyester input: PTA
Purified terephthalic acid prices inched up during the holiday week in Asian markets and were seen firming up further after reopening after the recess. In China, the Futures market was firm on the first trading day following the Spring Festival, while offers for spots and bids were higher than Futures. European spot market was quiet and prices generally remained unchanged at the moment, awaiting the resumption of Asian markets next week. In US, January contract prices decreased on weaker paraxylene contract prices for the month and modest downstream demand in the PET sector.
Asian PTA markers, the CFR China gained US$7 on the week to US$847-849 a ton while offer from Taiwan/Korea was up US$5 at US$865-875 a ton. In China, offers for bonded goods were around US$865-875 a ton discussions for nearby-month cargoes between US$820-840 a ton. Yisheng Petrochemical’s daily prices were at US$880 a ton and that of Hengli Petrochemical’s at US$860 a ton, both up US$10-20. In Europe, January contract prices were at Euro740-774 a ton FD NWE. In the US, January contracts were revised to US cents 49.71 per pound (US$1,096 a ton) from the previous month.
Nylon input: Caprolactam
Caprolactam markets in Asia were quiet during the Lunar New Year holiday. Prices of liquid materials in China generally rolled over as buyers picked need base volumes. The markets remained lusterless on the first working day after the holiday with prices unchanged for liquid and solid materials amid thin market liquidity. In Europe, caprolactam remained well supplied, despite earlier tightness concerns in upstream cyclohexane market. Demand was seasonally low, but balanced due to reduced downstream demand. In the US, caprolactam precursor, cyclohexane February contract price increased following gains in the benzene settlement last week. The contract price is calculated by formula, based on the monthly benzene contract and daily gas price.
Asian caprolactam prices rolled over on the week with SE and FE Asia markers at US$1,550-1,600 a ton. In China, spot prices for liquid goods remained unchanged at 12,700-12,900 Yuan a ton (US$1,895-1,925 a ton) while flake goods at 13,000-13,600 Yuan a ton (US$1,940-2,250 a ton). Sinopec’s February nomination for liquid goods were at 13,200 Yuan a ton (US$1,970 a ton), and Fibrant at 13,400 Yuan a ton (US$2,000 a ton). In Europe, January contracts had settled at Euro2,116-2,235 a ton FD NWE in the preceding week. In the US, precursor cyclohexane contract price for February increased US cents 6 to settle at US cents 218 a gallon FOB US Gulf.
Acrylic input: Acrylonitrile
Acrylonitrile markets in Asia were silent due to week-long Lunar New Year holidays and prices generally rolled over. Post-holiday trading activities slowly warmed up and most market participants took a sidelined stance as prices inched up in China. In Europe, acrylonitrile CIF ARA marker hit an eight-week high amid rising demand from the fibre and ABS sectors in Asia – particularly China – and Europe. Prices may find further support as two major European producers have announced planned turnarounds in Q2 coinciding with AnQore's plans for maintenance at its unit in Geleen, the Netherlands, in May. In the US, spot export acrylonitrile prices were steady this week amid slow demand in Asia due to holiday leaving little incentive for US producers to sell and instead adopt a wait-and-see attitude amid expectations that demand should improve after the holiday. Producers offers little incentive to sell material, but slower demand in the spot export market failed to garner higher bids for cargoes. Other sellers were focusing on contractual needs until the demand outlook becomes clearer.
Asian acrylonitrile Far East CFR marker was steady on the week at US$1,529-1,531 a ton while CFR China rolled over at US$1,400-1,450 a ton. In China, self-lifting values at Lianyungang port were also stable at US$1,760-1,790 a ton. However, on the first day after holidays, offers ran up US$30 at Lianyungang and also ranged higher between US$1.790-1,805 a ton delivered in Shandong. In Europe, prices were at US$1,218-1,220 a ton CIF Mediterranean while they were assessed at US$1,300 a ton CIF ARA, the highest since early December. In the US, spot export prices were flat at US$1,340-1,400 a ton FOB in the US Gulf. January domestic contracts were pegged at US cents 66.81-71.81 per pound (US$1,473-1,583 a ton) DEL US Gulf in the previous week.