Polyester input: MEG
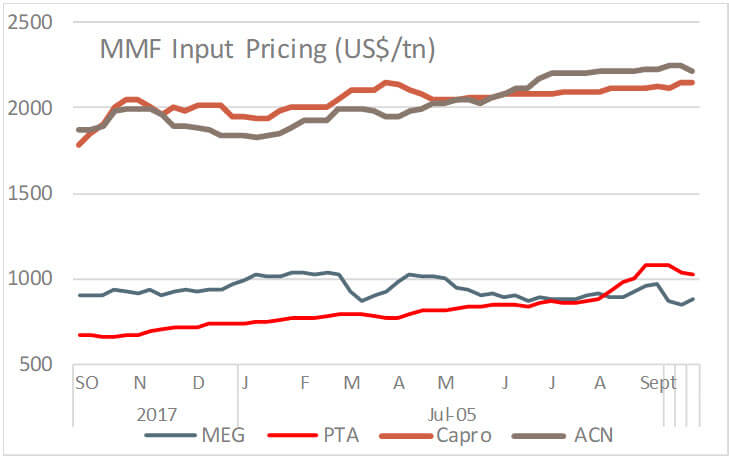
Mono ethylene glycol prices firmed up in Asian markets on the buoyant buying sentiment as downstream producers rushed to stock up ahead of the Golden Week holiday. In China, the wait-and-watch stance weakened gradually as there were lesser polyester producers amid maintenance this week. Meanwhile, the busy season will begin after the National Day holiday and large orders are expected to emerge. Meanwhile, inventories in east China increased to 568 kilo ton, up 18% from last week. Spot prices gained US$25 on the week to US$885-890 a ton CFR China and by US$40 to US$885-890 a ton CFR South East Asia. Sinopec cut its October list prices to 7,500 yuan a ton (US$1,090 a ton), down US$60 from the September settlement.
In Europe, mono ethylene glycol spot prices were stable-to-soft as supply was comfortable ending September and entering October. Sentiment was on a downslide due to increased imports in October of larger parcels, and prices were assessed lower in line with market feedback. Bulk spot prices were Euro 5 down at the lower end and stable at the upper, bringing prices to Euro 855-870 a ton CIF NWE. Truck prices were down Euro 5 at both ends, ranging Euro 895-910 a ton FCA NWE.
In US, mono ethylene glycol prices were steady, but peak demand will soon begin to slow down on seasonality. Supply was snug as all plants were in operation while demand into PET was good. MEG contracts for September rolled over at US cents 41.5-47.5 per pound FOB.
Polyester input: PTA
Purified terepthalic acid prices in Asia moved down slightly this week as supply started to increase with restart of large plants this week in China. The average operating rate rose to 82% in the week as Yisheng Petro, BP Zhuhai Petro and Jialong Petro restarted during the week. The surge in upstream paraxylene prices, however, limited the fall in PTA price.
Asian PTA markers edged down US$5 week on week with CFR China at US$1,020-1,022 a ton and offer from Taiwan/Korea falling to US$1,030-1,032 a ton. In China, prices for bonded goods were adjusted to US$1,050-1,100 a ton. Buyers bid for nearby-month cargoes at below US$1,000 a ton early in the week, while midweek saw sellers holding offers at US$1,040-1,050 a ton. Yisheng Petrochemical lowered its daily prices to US$1,050 a ton and Hengli Petrochemical’s self-lifting offer fell to US$1,100 a ton.
In Europe, PTA supply remained constrained and prices were stable, as paraxylene prices were up on Asian cues. Meanwhile, Indorama Portugal has planned a 10-day maintenance shutdown beginning October. This may constrain supply further, but wakening demand may neutralise the supply snug. PTA contract price were stable at Euro 763-797 a ton FD NWE.
Nylon input: Caprolactam
Caprolactam spot prices rolled over in Asian markets while contract were seen settling higher as feedstock benzene market was range bound and static demand. Run rates of polymerization units and yarn makers were running at 80%. Taiwan's China Petrochemical Development Corporation settled its October contract price as firm upstream phenol values are expected to support the price. China’s Sinopec settled its September contract price higher from August as domestic demand is expected to peak after its week-long National Day celebration in first week of October.
Asian markers rolled over this week with SE and FE Asia at US$2,150-2,200 a ton. In China, spot prices for liquid goods softened to 17,800-18,500 yuan a ton (US$2,590-2,690 a ton) while flake goods were at 18,100 yuan a ton (US$2,630 a ton). Taiwan's China Petrochemical Development Corporation settled its October contract price at US$2,240 a ton CFR NE Asia, up US$70 from September.
In Europe, September contract price rolled over amid balanced supply and demand conditions and stable downstream nylon 6 contract pricing month on month. Negotiations for cyclohexane Q4 contract price has started and supply and demand dynamics will tend to drive delta price negotiations. September contracts had settled at Euro2,272-2,433 a ton FD NWE rolling over from August.
Acrylic input: Acrylonitrile
Acrylonitrile markets in Asian witnessed dull trading and prices fell ahead of a week-long holiday. The China market will remain closed on 1-7 October for the National Day Golden Week holiday. The large downstream consumers, acrylic fibre and acrylonitrile-butadiene-styrene sectors were well-covered by contract volumes, while most of other small downstream buyers had finished stocking activities. As a result, transactions during the week were limited, and some traders were already away on holiday. Asian acrylonitrile markers fell US$30 on the week with Far East CFR back to US$2,219-2,221 a ton while CFR China was flat at US$2,200-2,230 a ton. In China, self-lifting values at Lianyungang port rolled over at US$2,760-2,775 a ton.
In Europe, acrylonitrile spot activity also remained limited and prices generally rolled over after the hike in September contracts last week and weak propylene this week. Spot prices remained unchanged at US$2,048-2,052 a ton CIF Mediterranean after September contract prices were settled Euro34 up at Euro 2,133-2,201 a ton FD NWE.
In US, acrylonitrile spot export prices were flat at US$2,110-2,130 a ton FOB USG as global supply remained tight. Two large units will go on turnaround each with capacities over 200,000 ton a year. This supply disruptions Q4 may assert upward pressure on US prices in the coming month. However, seasonal downturn in acrylic fibre and ABS is likely to offset supply tightness anticipated from October through Q4.