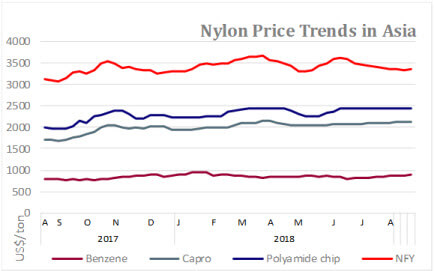
Nylon filament yarn markets were stable, given operating losses of some specs. Nylon FDY yarn prices held flat but were firm on the back of high chip prices but slightly thin demand, while nylon DTY prices rose on rising feedstock cost despite tepid demand. Demand was steady as textile producers operated at stable rates with thin liquidity of FDY, DTY and POY. Nylon FDY70D/24F SD prices rolled over on the week at 23.00-23.50 yuan a kg (US$3.35-3.42 a kg), while DTY70D prices increased to 23.80-24.80 yuan a kg (US$3.46-3.61 a kg, up US cents 5).
Warp knitting mills and covering mills were operating at 70% run rates, and circular knitting mills and lacing mills at 50%. Demand for cord fabric was ideal, while that for fishing net yarn and staple fibre was modest and fair for monofilament yarns. Cord fabric 1,260D prices offers were stable at 26.50-27.50 yuan a kg (US$3.86-4 a kg), while monofilament 30D prices rose to 24-25 yuan a kg (US$3.49-3.64 a kg), up US cents 8). Nylon staple fibre 1.5D prices were also raised to 20.20-20.60 yuan a kg (US$2.94-3.00 a kg, up US cents 2-4 on the week).
Nylon chip prices picked up in Asian markets this week on flat to higher caprolactam cost and operating margins remained positive. Demand for chip was steady, with nylon yarn marker operating at stable rates given positive profits. Buying appetite was modest, implying that demand was still rigid. Trading volume and prices of cord fabric were stable amid high profits, showing some demand for chip. Engineering plastics and film units also had stable demand for chip. Taiwan‐origin SD high-speed nylon chip prices inched up US$10 at the lower end to at US$2,440-2,450 a ton. In China, offers for conventional nylon-6 chip were hiked US$50 to US$2,635-2,710 a ton, while SD high-speed chip offers were up US$35 at US$2,665-2,750 a ton.
In Europe, the nylon market was silent with no major business done as players were slowly resuming operation after summer holidays. Supply was reportedly ample and demand a bit lower. July contracts for nylon 6 virgin polymer were steady at Euro 2.28-2.43 a kg FD NWE and nylon 6,6 virgin polymer in the range of Euro 3.93-4.34 a kg FD NWE.
Caprolactam prices in Asian markets were stable to firm this week as tight supply in the region continued to lend support for the higher price. In China, prices for domestic liquid goods inched up, while flake material prices currently remain steady. Sinopec, however, settled its August contract lower than nomination while Japan's Sumitomo settled August contract slightly higher from July on CFR NE Asia basis. Demand was steady as run rates of polymerization units were at 80% and yarn makers at 82%. Asian markers rolled over with SE and FE Asia at US$2,120-2,160 a ton. In China, spot prices for liquid goods were slightly up at 16,900-17,200 yuan a ton (US$2,460-2,500 a ton, up US$20). Japan's Sumitomo Chemical settled its August caprolactam contract price up US$5 from July at US$2,165 a ton CFR NE Asia.
In Europe, the caprolactam market was quiet as players were slowly returning back from holidays. Contract discussions for August will continue in view of ample supply and demand mostly down due to the summer slowdown. July contracts were at Euro 2,282-2,443 a ton FD NWE.
Benzene prices in Asia fluctuated slightly this week as demand softened from downstream styrene monomer, phenol and acetone markets. Lack of buying interest also prompted cargo-holders to cut offers, slightly dragging down discussion levels. Falling inventories at ports, however, supported the benzene market in China. Inventories at shore tanks along east China fell 1.8% to 161 kilo tons. Spot benzene prices inched up US$6 on the week with CFR China at US$895.50-896.50 a ton and FOB Korea at US$886.50-887.50 a ton.
In Europe, the benzene market was well-supplied, and with a force majeure at Covestros Maasvlakte Netherlands, styrene unit, benzene consumption was reduced in the past few weeks. Around 30-40 kilo tons of benzene is expected to load in ARA region, headed for US Gulf before the end of August. Spot declined US$12.50 on the week, with both FOB Rotterdam and CIF values at US$857.50-858.50 a ton.
In the US, benzene spot prices were assessed narrower as deals for August and September shipment clustered around a single price point. Supply lengthened on high refinery operating rates and influx of fresh cargoes from Europe, while demand from most derivatives was strong. Prompt month spot prices were assessed US cents 2 down on the week at US cents 293.95-294.05 a gallon FOB USG.