Polyester
Polyester filament producers gradually resumed operations in China, although downstream mills were yet to begin buying activity, citing the labour shortage and the stocks in hand. In Shengze, producer kept prices stable, with most offers rolling over. In Zhejiang, firmer crude oil against the further decline in purified terephthalic acid futures and filament prices were generally stable, with sporadic price reductions seen in some spec amid thin trading atmosphere and low buying interest. In Pakistan, polyester DTY sales were insipid on the back of poor polyester feedstock and import values. In India, producers’ offers for POYs remained unchanged amid stable market sentiment. Firm deals remained sparse, as downstream mills were on a wait-and-see stance, without intention to store up materials.
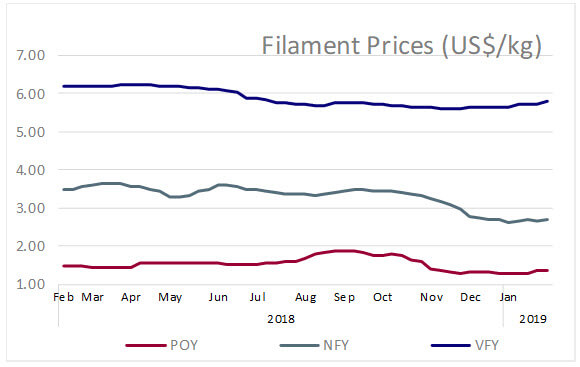
In China, PFY offers rolled over in Yuan terms and down US cents 1-2 in US$ terms. In Shengze, offers for POY 75/72 were at US$1.36-1.38 a kg and 75/36 at US$1.35-1.36 a kg. In India, too, POY offers rolled in INR and US$ terms, with 115/108 at INR100 a kg or US$1.40 a kg and 130/34 POY at INR92 a kg or US$1.29 a kg. In China, DTY prices of 75/72 intermingled DTY were at US$1.85-1.86 a kg and 75/36 at US$1.83-1.85 a kg in Shengze. In Pakistan, selling indications for 300/96 DTY local goods were at PakRs107 a pound while 150/48 DTY intermingled local goods were down PakRs4 at PakRs114 a pound (US$1.80 a kg, down US cents 7). In China, FDY offers for 50/24 were at US$1.54-1.55 a kg and 150/96 FDY at US$1.46-1.48 a kg.
Nylon
Nylon filament yarn prices jumped in Asian markets as caprolactam spot and contract values both moved higher and chip prices gained. Downstream textile producers were resuming operation, though some smaller mills have not restarted yet. Warp knitting mills and covering mills operated at 45 % run rates, while circular‐knitting mills and lacing mills ran lower at 15% run rates. Demand for staple and monofilament improved a bit, while that for fishing net yarn may remain was modest, and cord fabric decent. Nylon‐6 FDY prices inched higher tracking chip gains and suppliers reported fair margin. Nylon 6 DTY prices were stable‐to‐firm, with downstream demand slowly returning. Prices of cord fabric rose while monofilament was traded at a roll over on decent demand, with low‐end prices less available.
In China, offers were raised in Yuan terms but stronger US$ partially negated the increases. Nylon FDY70D/24F SD offers were raised at eh lower end to 18.50-19.00 Yuan a kg (US$2.74-2.81 a kg), while DTY70D offers were hiked at the upper end to 19.50-21.30 Yuan a kg (US$2.88-3.15 a kg) both up US cents 2 at the respective ends. Cord fabric 1,260D offers were raised to 23.00-24.50 Yuan a kg (US$3.40-3.62 a kg, up US cents 5) while mono filament 30D prices were stable at 20.50-21.50 Yuan a kg (US$3.03-3.18 a kg, down US cents 2). In India, 20 SD filament prices were steady on the week at INR296 a kg (US$4.15 a kg) in Surat market.
Viscose
Viscose filament yarn market were yet to recover after the Spring Festival in China as downstream converters were gradually resuming operation in the latter half of the week. Producers mostly raised offers although no firm deals were concluded at those levels yet. Price-wise, offers for first-class, second-class and third-class 120D were seen rolling over on the week. Some firm deals are expected to be concluded in coming week, following the gradually resumption of production in downstream sector, but focus will be on actual trading prices. In India, viscose filament yarn prices did not move, lacking cost or demand support at the moment.
In China, offers for viscose filament 120D bright notionally rolled over at 38.80 Yuan a kg (US$5.78 a kg), and dull at 38.45 Yuan a kg (US$5.73 a kg). 300D bright prices were at 29.20 Yuan a kg (US$4.35 a kg) and dull at 25.70 Yuan a kg (US$3.83 a kg). In India, VFY prices were unchanged, with 100D bright VFY at INR388 a kg (US$5.44 a kg) and 450D at INR 225 a kg (US$3.16 a kg). All quotes were down US cent 1 due to stronger US$.