Polyester
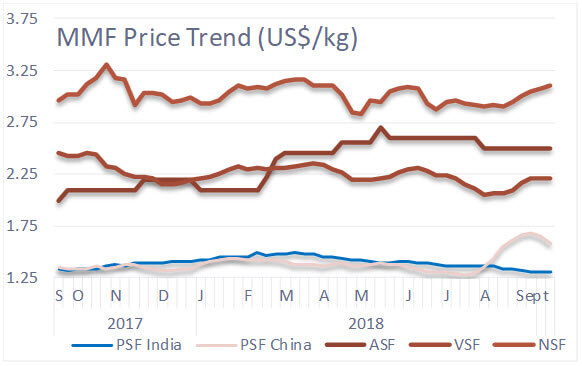
Polyester staple fibre producers in China cut down offers on bearish sentiment, leading to tepid trading sentiment. Mainstream discussions for 1.4D direct-melt-spun PSF in Jiangsu and Zhejiang fell during the week seeing upstream PTA and MEG prices retreating sharply. In Shandong and Hebei, polyester fibre markets turned weak lacking bullish factors while offers softened further in Fujian. In Jiangsu and Zhejiang, offers for 1.4D direct-melt PSF were cut to 10.80-11.10 yuan a kg (US$1.58-1.62 a kg, down US cents 8) while the same in Fujian and Shandong were down US cents 6-9 at US$1.59-1.64 a kg. Export offers, were also reduced to US$1.35-1.40 a kg FOB China.
In Pakistan, producers offers remained unchanged after three straight weeks of hike as cost of raw material in international were falling rapidly. 1.4D PSF offers were at PakRs.198-200 a kg (US$1.61-1.62 a kg).
In India, offers remained unchanged for the month both in INR and US$ terms with 1.2D at INR95 a kg (US$1.31 a kg) and 1.4-2D at INR93.75 a kg or US$1.30 a kg.
Nylon
Nylon staple fibre 1.5D prices were raised at the lower end to 21.20-21.50 yuan a kg (US$3.10-3.15 a kg, up US cents 3).
Acrylic
Acrylic staple fibre prices remained unchanged this week as producers struggled with high input cost seeing no end. In China, though fibre producers shut down units to resist high feedstock cost, acrylonitrile producers in upstream persisted holding offers firm, while downstream yarn mills were watching for any huge risk coming down from ACN sector, despite they suffered losses when goods were piled up as inventory. As situation stand, the entire industry chain is conflicted, as producers find themselves trapped at both ends, and losing confidence in the interim. The run rate has fallen to 38% during the week, as most units were idled, and some operating at reduced rate. But overall demand was weak, with some improvement seen in core-spun yarn markets but could hardly boost buying interest. Taiwan origin 3D bright ASF tow offers rolled over at US$2.50-2.60 a kg while offers in China for medium-length and cotton-type acrylic fibre were stable at 20.50-21.90 yuan a kg (US$3.00-3.07 a kg).
Prices in India and Pakistan rolled over again after recent price hikes. In India, producers’ offers were steady at INR194-205.50 a kg (US$2.70-2.86 a kg) for September. In Pakistan, 1.2D ASF prices remained unchanged in Karachi market at PakRs.360 a kg (US$2.92 a kg).
Viscose
Viscose staple fibre market remained stalemated, seeing offers stable to weak in Asian markets. Buying interest weakened as some producers had mostly fulfilled previous orders, and in turn liquidated volumes with discounts. Downstream yarn markets were generally stable and prices mostly rolled over. Offers for medium-end viscose goods were stable at 15-15.40 yuan a kg (US$2.19-2.25 a kg), with trading price at 15.00-15.30 yuan a kg (US$2.19-2.24 a kg). Offers for high-end goods were at 15.30-15.40 yuan a kg (2.24-2.25 a kg). In spot, 1.5D VSF offers were at 15.10 yuan a kg (US$2.21 a kg) and 1.2D inched up to 15.30 yuan a kg (US$2.24 a kg).
In Pakistan, offers were rolled back after they were hiked in early August. Downstream demand was apparently weak and the hike had only increased the cost since spinners were unable to pass on cost. Offers for 1.5D VSF rolled back PakRs5 to PakRs270-273 a kg (US$2.19-2.22 a kg, down US cents 4) in Karachi. In India, 1.2-2.0D VSF prices rolled over at INR144-151 kg (US$2.00-2.10 a kg).