Polyester
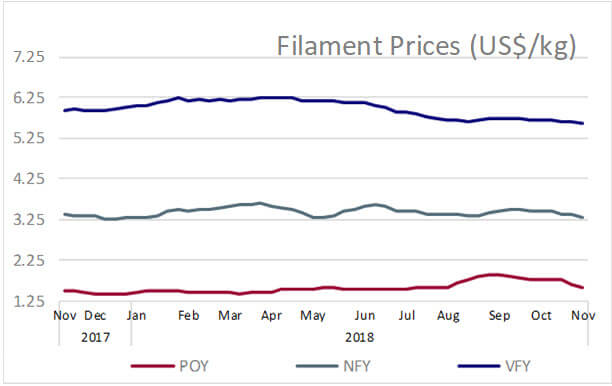
Polyester filament yarn markets in China extended the declines of the previous weekend, opening this week as prices fell sharply but remained steady in the later part of the week. The weekend saw PTA futures boosting local sentiment, although offers remained unchanged. Downstream mills increased buying to some extent but adopted a wait-and-see stance towards market future. In Pakistan, offers for imported goods fell and local offers were revised at par. Local sentiment warmed up slightly as producers focused on liquidity. In India, the POY market sentiment was stalemated and offers were reduced further, with deals negotiable based on volumes. Downstream mills remained production-steady with promotions continuing but were narrow.
In China, POY offers declined by US cents 4 in Shengze, with 75/72 at US$1.37-1.38 a kg and 75/36 to US$1.35-1.37 a kg. In India, POY offers were cut INR 4, with 115/108 at INR90.50 a kg or US$1.26 a kg and 130/34 POY at INR92 a kg or US$1.28 a kg, both down US cents 4. In China, 75/72 intermingled DTY prices fell US cents 6 to US$1.84-1.86 a kg and 75/36 to US$1.83-1.84 a kg. In Pakistan, selling indications for local and imported goods were down for 300/96 DTY intermingled at PakRs118 a kg (US$1.93 a kg) and imported goods to PakRs116 (US$1.90 a kg). In China, FDY offers fell US cents 4 for 50/24 at US$1.50-1.51 a kg and by US cents 2 for 150/96 FDY at US$1.31-1.33 a kg.
Nylon
Nylon filament yarn prices dipped as the caprolactam spot market was insipid and contract prices fell, while nylon chip prices trended downwards. Demand was hard to improve since textile producers operated at low run rates. The purchase of FDY, DTY and POY were based on rigid demand, while warp knitting and covering mills ran at 60% run rates. Circular knitting and lacing mills were operating at 40% run rates. Nylon FDY prices dipped on softening chip market and modest downstream demand while nylon DTY market was weak on low feedstock cost and tepid downstream demand. Falling chip markets will weigh on the yarn market as run rates of yarn makers was below 80%, keeping supply thin. Buying appetite was somewhat prudent and thus, nylon filament prices may dip further in coming week.
In China, offers for nylon FDY70D/24F SD fell to 22-23 Yuan a kg (US$3.17-3.32 a kg, down US cents 8), while DTY70D offers declined to 23.00-24.50 Yuan a kg (US$3.32-3.53 a kg, down US cents 12). Cord fabric 1,260D offers were flat at 26.50-27.50 Yuan a kg (US$3.82-3.96 a kg) while mono filament 30D prices rolled over at 23-23.50 Yuan a kg (US$3.32-3.46 a kg). In India, 20 SD filament prices were stable on the week at INR310 a kg (US$4.32 a kg) in Surat market.
Viscose
Viscose filament yarn offers were stable to down in China on the whole, but actual trading prices fell slightly given weaker buying interest of downstream converters who faced tight capitals towards the year end. Reportedly, some mainstream producers enjoyed passable liquidity, but inventory at some others increased a bit. Price-wise, offers for first-class, second-class and third-class VFY 120D were seen inching down a bit and trading prices eased, due to slow liquidity. In India, viscose filament prices rolled over on the week. Given the approaching year-end, demand for viscose filament appears weak, resulting in slow liquidity. Thus, prices are expected to remain range bound on a weak note in coming weeks.
In China, offers for viscose filament 120D bright were down at 38.80 Yuan a kg (US$5.59 a kg), and dull at 38.45 Yuan a kg (US$5.54 a kg). 300D bright prices moderated to 29.20 Yuan a kg (US$4.21 a kg) and dull to 25.70 Yuan a kg (US$3.70 a kg). All quotes were down US cents 4 on the week. In India, VFY prices remained unchanged in INR and up US cents 4-7 in US$ terms, with 100D bright VFY at INR388 a kg (US$5.40 a kg) and 450D at INR 225 a kg (US$3.13 a kg).