Polyester
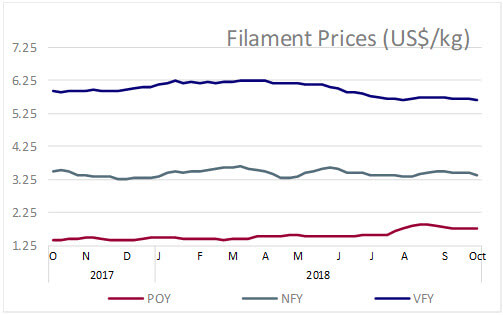
Polyester filament yarn prices moved in different directions this week in China. POY prices rolled over, while DTYs were dearer and FDYs cheaper. These conditions imply that the peak season is tapering, and most end-uses are close to meeting their order book. Poor performance of upstream purified terephthalic acid and PET markets, prompted PFY makers to adjust lower amid insipid trades. Downstream mills were mainly consuming their raw material inventories and purchased only to cover immediate use. POY offers were flat in Shengze with 75/72 at US$1.77-1.79 a kg and 75/36 at US$1.74-1.76 a kg. 75/72 intermingled DTY prices were up US cent 1 US$2.19-2.21 a kg and 75/36 up US cents 5 at US$2.19-2.21 a kg. FDY offers were down with 50/24 at US$1.79-1.80 a kg, down US cents 9, while 150/96 FDY were stable at US$1.61-1.63 a kg.
In Pakistan, the sharp depreciation in the currency forced local polyester filament suppliers to raise their offers closer to import parity, although prices of imported goods did go up further this week. However, the gap has narrowed down significantly. Selling indications were raised by PakRs36 300/96 DTY intermingled local goods to PakRs116 a kg (US$1.93 a kg, up US cents 58) and imported goods by PakRs7 to PakRs118 (US$1.96 a kg, up US cents 10).
In India, POYs offers rolled over this week after they were cut for October with 115/108 at INR104 a kg or US$1.42 a kg and 130/34 POY at INR96 a kg or US$1.31 a kg.
Nylon
Nylon filament yarn prices were corrected down in line with the dipping chip market, while operations in terminal markets were cautious. Warp-knitting, weaving and AJ covering sectors operated at 70% of rates while, circular-knitting and lacing mills ran at 45% capacities. Overall, nylon yarn market was weak. Feedstock market also dropped, easing cost pressure, while downstream buying demand was tepid amid fair margins. Nylon-6 FDY prices were down as demand from wool spinning sector was tepid and that from weaving sector passable. Nylon-6 DTY prices were flat at lower end amid modest demand, while production was slightly above break-even levels. Cord fabric and monofilament prices were down as margins were still good.
In China, offers for nylon FDY70D/24F SD dropped to 23.50-24 Yuan a kg (US$3.39-3.46 a kg, down US cents 6-9), while DTY70D offers fell at eh upper end to 24.50-25 Yuan a kg (US$3.53-3.68 a kg, down US cents 9). Cord fabric 1,260D offers declined to 27-28.00 Yuan a kg (US$3.89-4.04 a kg, down US cents 9) while mono filament 30D prices declined to 23.80-24.00 Yuan a kg (US$3.43-3.46 a kg, down US cents 11-16). Nylon staple fibre 1.5D prices were also down at 19.50-20.60 Yuan a kg (US$2.81-2.97 a kg, down US cents 14). In India, 20 SD filament prices remained unchanged this week at INR300 a kg (US$4.09 a kg) in Surat market.
Viscose
Viscose filament yarn prices were stable in China, while firm trading atmosphere improved somewhat, seeing good liquidity of high-end goods. During the week, offers for first-class, second-class and third-class goods were rolled over from the previous week. Producers retained their selling indications, seeing fresh offers for dissolving pulp firming up in domestic as well as for imported material which can translate into higher cost later. Thus, attention was paid to downstream follow-ups at the moment. In India, no changes were made in viscose filament yarn prices as demand was stagnant and cost high.
In China, viscose filament offers were stable with 120D bright at 39.30 Yuan a kg (US$5.66 a kg), and dull at 38.95 Yuan a kg (US$5.61 a kg). 300D bright were flat at 29.75 Yuan a kg (US$4.29 a kg) and dull at 26.25 Yuan a kg (US$3.78 a kg). All quotes were down US cents 2 due to weak Yuan. In India, VFY prices were stable in INR terms and up US cents 1-3 in US$ terms, with 100D bright VFY at INR388 a kg (US$5.28 a kg) and 450D at INR 225 a kg (US$3.06 a kg).