Polyester
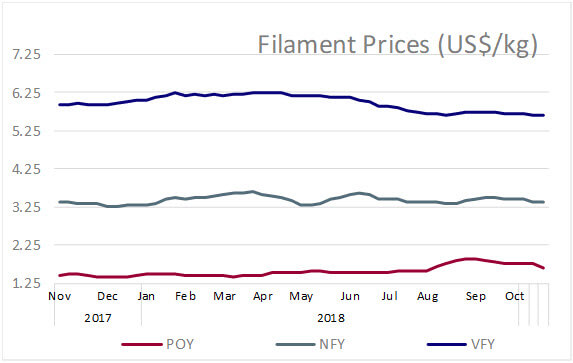
Polyester filament yarn prices declined sharply in China, pressured by the poor performance of crude oil and PTA and MEG price. Producers were eager to offload goods due to rising inventory pressure while downstream mills mainly covered shorts. Prices of POYs and DTYs were seen falling faster while the pace of decline was slower in the case of FDYs. In Zhejiang, transaction was insipid, and inventory kept rising, as downstream mills just stood on the sidelines. PFY sales were thin in Jiangsu and Zhejiang, while sales/production ratios were at 40-60%. POY offers declined sharply by US cents 17 in Shengze with 75/72 at US$1.41-1.43 a kg and 75/36 at US$1.40-1.41 a kg. 75/72 intermingled DTY prices fell US cents 17-19 at US$1.90-1.92 a kg and 75/36 to US$1.89-1.90 a kg. FDY offers fell US cents 10 for 50/24 at US$1.54-1.56 a kg and by US cents 7 for 150/96 FDY at US$1.33-1.34 a kg.
In Pakistan, DTY market sentiment was dismal, seeing thin transactions and overall demand withering. Selling indications for DTY intermingled were heard rolling over and at par with imported goods. Selling indications for local goods were stable for 300/96 DTY intermingled at PakRs120 a kg (US$1.97 a kg) and imported goods at PakRs118 (US$1.94 a kg).
In India, due to the weakness of crude oil and PTA, local POY prices remained unchanged amid muted trading atmosphere. POY offers were flat, with 115/108 at INR94.50 a kg or US$1.30 a kg and 130/34 POY at INR96 a kg or US$1.32 a kg.
Nylon
Nylon filament yarn prices dipped this week as the upstream caprolactam market was insipid and contract prices were high, while nylon chip price movements were divided. Demand was rigid as textile producers operated at low run rates. Purchasing volume of FDY, DTY and POY were need based. Warp knitting mills and covering mills ran at 65% run rates, and circular knitting and lacing mills run at 45%. Nylon FDY prices dipped on softening chip market and thin demand from terminal sectors. The nylon DTY market was weak on low feedstock costs, while demand was tepid. Prices of cord fabric and monofilament yarn declined, while prices of staple fibre rose at the lower end amid passable demand. Overall, buying appetite for nylon filament was somewhat prudent, thus prices may dip in the coming week.
In China, offers for nylon FDY70D/24F SD drifted to 22.50-23.50 Yuan a kg (US$3.25-3.39 a kg, down US cents 7), while DTY70D offers fell at the upper end to 23.80-24.80 Yuan a kg (US$3.43-3.58 a kg, down US cents 3). Cord fabric 1,260D offers were down at 26.50-27.50 Yuan a kg (US$3.82-3.97 a kg, down US cents 7) while mono filament 30D prices declined similarly to 23.00-23.50 Yuan a kg (US$3.32-3.46 a kg). In India, 20 SD filament prices were flat on the week at INR310 a kg (US$4.26 a kg) in the Surat market.
Viscose
Viscose filament yarn offers were largely stable. As the year end draws closer, downstream mills and end users were facing heavy pressure from inventory and capitals. Hence, they were actively destocking materials. However, buying interest was weak, and consumers mainly bought volume on need-to basis. Price-wise, offers for first-class, second-class and third-class VFY 120D were seen stable while coarser yarns were cheaper. However, trading prices partly eased, due to slow liquidity. In India, viscose filament prices remained unchanged on the week. Overall, with year ending approaching, demand appears weak, resulting in slow liquidity. Thus, prices are expected to remain range bound on a weak note in coming weeks.
In China, viscose filament offers for 120D bright were stable at 39.00 Yuan a kg (US$5.63 a kg), and dull at 38.65 Yuan a kg (US$5.58 a kg). 300D bright prices moderated to 29.42 Yuan a kg (US$4.257 a kg) and dull to 25.92 Yuan a kg (US$3.74 a kg), both down US cents 2. In India, VFY prices rolled over in INR and up US cent 1 in US$ terms, with 100D bright VFY at INR388 a kg (US$5.33 a kg) and 450D at INR 225 a kg (US$3.09 a kg).