Polyester
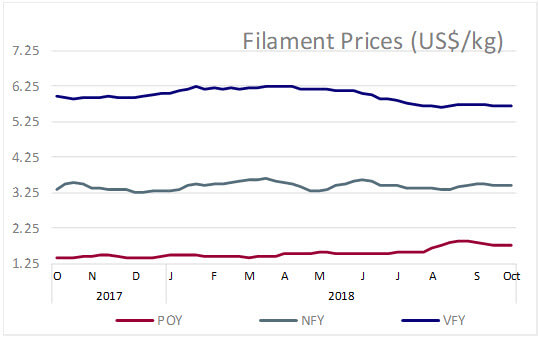
Polyester filament yarn prices were hiked in China across specs and luster as the market became more active with procurement in the domestic market. Inventory levels of certain filament yarn grades were low, and there were some expectations for operating rates to be raised in the H2 October to meet the traditional peak demand period. However, crude oil and raw materials, local trading atmosphere was thin, while offers stayed unchanged weekend. Participants generally held a bearish outlook, citing that downstream mills were consuming their stocks. POY offers were hiked in Shengze with 75/72 at US$1.78-1.79 a kg and 75/36 at US$1.75-1.77 a kg, up US cent 1. 75/72 intermingled DTY prices were at US$2.18-2.20 a kg and 75/36 at US$2.14-2.16 a kg. FDY offers were up over with 50/24 at US$1.88-1.90 a kg, up US cents 2 and 150/96 FDY at US$1.62-1.63 a kg, up US cent 1.
In Pakistan, DTY sales remained insipid while offers in US$ terms declined due to sharply fall in the PakRe. Selling indications were stable for 300/96 DTY intermingled local goods at PakRs80 a kg (US$1.35 a kg) and imported at PakRs111 (US$1.99 a kg), down US cents 8-12 due to sharp fall in the currency.
In India, POY offers were held stable after they were cut last week for the month. Sentiment was stable, with still some discounts, as downstream mills maintained hand-to-mouth procurement, holding wait-and-watch stance during the negotiations for fresh orders. Offers were stable, with 115/108 at INR104 a kg or US$1.41 a kg and 130/34 POY at INR96 a kg or US$1.30 a kg.
Nylon
Nylon filament yarn prices were stable this week in Asia, while the insipid chip market led to decline in staple and monofilament prices. Filament market was supported by chip contract prices. Plant run rates of yarn makers was at 81%, keeping supply tight, with inventory at normal levels of 15 days’ worth. Weak buying appetite was adding to inventory pressure. Downstream converters operated at flat run rates and buying interest for FDY, DTY and POY was limited. Warp knitting mills and covering mills operated at 60% run rates, while circular knitting mills and lacing mills at 45%. Nylon FDY prices were firm on the back of higher chip prices while DTY prices were stable on high feedstock cost. Downstream demand was still tepid.
In China, offers rolled over for nylon FDY70D/24F SD at 23.80-24.50 Yuan a kg (US$3.44-3.54 a kg), while DTY70D offers were at 24.50-26.00 Yuan a kg (US$3.54-3.76 a kg), both down US cents 2 due to weak Yuan. Cord fabric 1,260D offers were at 27.50-28.50 Yuan a kg (US$3.98-4.12 a kg), while mono filament 30D prices declined to 24.50-25.00 Yuan a kg (US$3.54-3.62 a kg, down US cents 9). Nylon staple fibre 1.5D prices were down at 20.50-21.50 Yuan a kg (US$2.97-3.11 a kg). In India, 20 SD filament prices remained unchanged this week at INR300 a kg (US$4.07 a kg) in Surat market.
Viscose
Viscose filament prices were largely stable this week in China as downstream mills replenished some volumes to cover their basic needs after the week-long holidays. Thus, trading atmosphere improved somewhat. However, smooth sales was reported for first-class goods with steady sale/production ratio. Price-wise, offers for first-class, second-class and third-class VFY 120D were seen rolling over from their firm level before the holidays. In India, viscose filament prices were generally stable, and may remain at the levels in the short-run.
In China, VFY offers rolled over with 120D bright at 39.30 Yuan a kg (US$5.69 a kg), and dull at 38.95 Yuan a kg (US$5.64 a kg). 300D bright were flat at 29.75 Yuan a kg (US$4.30 a kg) and dull at 26.25 Yuan a kg (US$3.80 a kg). All quotes were down US cents 2-3 due to weak Yuan. In India, VFY prices were stable in INR terms and down US cents 1-2 in US$ terms, with 100D bright VFY at INR388 a kg (US$5.26 a kg) and 450D at INR 225 a kg (US$3.05 a kg).