Polyester input: MEG
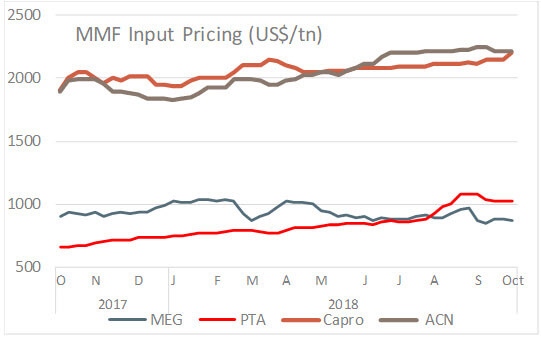
Mono ethylene glycol markets in Asia opened the week with prices increasing on strong buying activities amid buoyant futures post-holiday. Improved margins for polyester and uptick in sales with production decline built expectations that these gains would improve demand for MEG post-holiday. Nonetheless, the increase in price was moderate as activity remained largely muted. Prices plunged on Thursday as overall market sentiment weakened, with most commodities Futures on Dalian and Zhengzhou exchanges declining. However, discussions picked up on the weekend amid stock building activities in China’s domestic market. Meanwhile, inventories in east China increased 0.5% to 571 kilo ton. Spot prices were down US$10-12 on the week with CFR China at US$873-878 a ton and CFR South East Asia at US$75-880 a ton.
In Europe, the September contract was confirmed at increase from August, while an initial October contract was also agreed alongside, but was not followed. Spot bulk prices were flat at Euro 850-865 a ton CIF NWE while truck spot prices rolled over at Euro 890-905 a ton FCA NWE. September MEG contract was confirmed at Euro 1,012 a ton FD NWE, up Euro 13 from August levels.
In the US, MEG spot was steady as supply and demand remain in balance. But there was downward pressure as demand softened after the end of peak season. Contracts for September rolled over at US cents 41.5-47.5 per pound FOB. Domestic spot prices were quoted in the upper-US cents 30 per pound for barge material and lower-US cents 40 per pound for rail/truck material.
Polyester input: PTA
Purified terephthalic acid markets were under downward pressure due to availability of competitively-priced cargoes in the domestic market of China. The arbitrage economics for imports into China was closed due to relatively lower prices in local market. Market participants were optimistic about the outlook for domestic prices with the recent rebound in the PTA futures market. Further, supply was described as tight on the back of steady sales achieved in downstream polyester markets. A heavy maintenance season is expected to begin from third week of October, and the increase in run rates of polyester units is also expected to emerge in second or the third week. Thus, markets will not see any downward room. PTA markers rolled over with CFR China at US$1,020-1,022 a ton and offer from Taiwan/Korea at US$1,030-1,032 a ton. In China, offers for bonded goods were maintained at US$1,050-1,100 a ton and discussions were at US$1,020-1,050 a ton.
In Europe, purified terephthalic acid market was waiting for the outcome of October paraxylene contracts before finalising 2019 contract negotiations. Production costs are up for PTA while downstream PET margins were good. September contract was at Euro 904-938 a ton FD NWE.
In the US, MEG spot was steady as supply and demand remain in balance. But there was downward pressure as demand softened after the end of peak season. Contracts for September rolled over at US cents 41.5-47.5 per pound FOB. Domestic spot prices were quoted in the upper-US cents 30 per pound for barge material and lower-US cents 40 per pound for rail/truck material.
Caprolactam spot trade in China was muted opening this week despite expectations that buying interest would pick up after the Golden Week National Day holidays. Trade was limited as market players were largely in wait-and-see mode due to market uncertainty in the downstream nylon market. Major producer Sinopec increased its list price from its settled price for September contracts. Prices picked up later to post weekly gains while domestic prices in China remained below previous week’s level. Caprolactam markers gained this week with SE and FE Asia at US$2,200-2,220 a ton. In China, spot prices for liquid goods softened to 17,700-18,000 Yuan a ton (US$2,560-2,605 a ton) while flake goods were at 18,000 Yuan a ton (US$2,605 a ton). Sinopec nominated October contract at 18,300 Yuan a ton (US$2,650 a ton) for liquid goods while Fibrant settled its issued September contract at 18,050 Yuan a ton (US$2,610 a ton).
In Europe, negotiations for October caprolactam contract remained inconclusive, as upstream remained sluggish. Meanwhile cyclohexane contract were settles following Q4 delta contract price fully confirmed last week at a decrease from the previous quarter. Caprolactam producer, Domo Caproleuna carried out planned maintenance at German facility in September. September contracts had settled at Euro2,272-2,433 a ton FD NWE rolling over from August.
Acrylic input: Acrylonitrile
Acrylonitrile discussions were weak in Asian markets this week due to amply supply in north China. There were no exact bids in both markets as buyers stayed on sidelines. Reportedly, a northeast producer dumped its cargo due to inventory pressure, which triggered a consecutive drop in prices this week. In the import market, dollar-dominated prices may drop as well due to some lower offers heard in the week. Asian markers were flat on the week with Far East CFR at US$2,219-2,221 a ton while CFR China was at US$2,200-2,230 a ton. In China, self-lifting values at Lianyungang port fell US$70 to US$2,690-2,705 a ton.
In Europe, spot prices dropped US$20 at US$2,068-2,072 a ton CIF Mediterranean, while negotiations for October contract price were ongoing on the sidelines of EPCA event. Two deals were closed at a double-digit hike corresponding to monthly increase of propylene and ammonia. Market remained tight, caused by two production turnarounds taking place in October, as well as limited imports from Asia.
In US, spot export prices for acrylonitrile were steady as the market continued to gauge the global supply demand outlook for Q4. Supply was tight in US as producers focused on building inventories for 2019 by over selling material in the spot export market. Spot export prices were at US$2,130-2,150 a ton FOB USG while domestic contracts were at US cents 81.07-85.07 per pound (US$1,787-1,875 a ton) DEL US.