Polyester input: MEG
Mono ethylene glycol prices declined in Asia on weak market sentiment, despite an uptick in polyester sales and gains in crude oil prices. A sharp uptrend in co-polyester feedstock purified terephthalic acid futures prices weighed on MEG buying indications, over concerns of possible increases in cost pressure for polyester producers. Nevertheless, the buying appetite for MEG remained relatively healthy following the decline in polyester inventory levels. MEGlobal reduced its January contract for Asia citing spot to have been under pressure amid volatile crude oil and lackluster downstream polyester sales. In Europe, the December contract price remained unconfirmed as sellers and buyers remain in discussion. Market fundamentals were still weak, with pressure on truck spot prices still apparent. Spot activity in bulk market was quiet and prices were assessed stable while truck spot prices slipped. Demand from antifreeze sector was ticking along in line with expectations. In US, MEG market was quiet and prices generally rolled over.
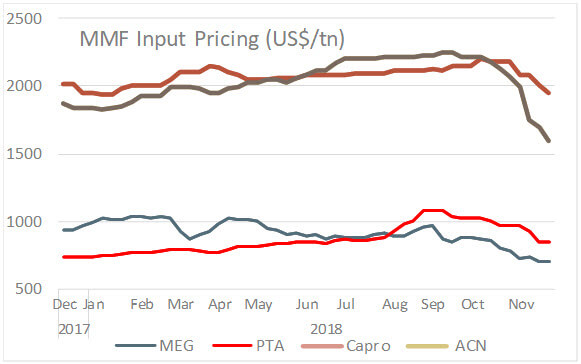
Asian spot benchmark lost US$24 on the week, with CFR China at US$681-686 a ton and CFR South East Asia at US$680-685 a ton. In China, offers for nearby-month cargoes fell to USS$690 a ton from US$725 a ton last week, while bids and discussions were at US$685 a ton. MEGlobal announced its January contract price at US$900 a ton CFR Asia, down US$50 from December nomination. In Europe, bulk spot prices were assessed at Euro680-700 a ton CIF NEW, while truck spot prices slipped Euro20 at the low end and Euro15 at the high, pegging the range at Euro720-770 a ton FCA NWE. In the US, November contracts were assessed at US cents 36.5-42.5 per pound FOB.
Polyester input: PTA
Purified terephthalic acid prices moderated in Asian markets as upstream paraxylene and crude oil markets moved either ways during the week. In China, PTA futures rose as some supplier bought goods amid sound trading atmosphere. In China, prices changed marginally as offers for bonded goods and spot cargoes were almost stable. Going ahead, concentration will be on replenishment ahead of year end that may result in boosting prices. Besides, possibility of further delay of maintenance would be a concern as market will generally be in a rebounding cycle in the short run. In Europe, purified terephthalic acid December contract decreased, moving alongside a drop in the paraxylene contract for the month.
Asian PTA markers the CFR China edged down US$4 on the week to US$846-848 a ton while offer from Taiwan/Korea was down US$5 at US$855-895 a ton. In China, offers for bonded goods were at US$850-900 a ton and cargoes at US$860-870 a ton. Yisheng Petrochemical’s daily prices were unchanged at US$900 a ton, while that of Hengli Petrochemical’s at US$850 a ton. In Europe, the December contract price was down by Euro67 to reach Euro770-804 a ton FD NWE. In the US, November contracts were at US cents 54.40 per pound (US$1,199 a ton) DEL USG.
Caprolactam
Caprolactam spot markets in Asian went weak amid waning demand for downstream products, as well as softer feedstock benzene values. In China, offers for liquid and flake materials declined sharply on lukewarm downstream demand. Japan’s Ube Industries settled its December caprolactam contract price lower from November, citing weak demand and feedstock values. In Europe, the December contract talks continued, and early agreements were heard at triple-digit decreases, following the sharp drop in benzene this month. Due to the shorter working month, players were aiming to finish the remaining monthly discussions before the end of the year. There was continued pressure in the downstream nylon 6 market in terms of pricing but talks remained ongoing. Meanwhile, caprolactam sellers and buyers were debating the level of decrease with mention of full benzene decrease to be passed on downstream.
Asian caprolactam prices plunged further by US$150 on the week, with SE and FE Asia markers at US$1,650-1,700 a ton. In China, spot prices for liquid goods fell to 13,000-13,500 Yuan a ton (US$1,890-1,965 a ton, down US$105), while flake goods fell to 13,500-14,000 Yuan a ton (US$1,965-2,035 a ton, down US$75). Japan's Ube Industries settled its December contract price at US$1,910 a ton CFR NE Asia, down US$240 from November. In Europe, November contract prices were assessed at Euro2,256-2402 a ton FD NWE. In US, December cyclohexane settled at US cents 256 per gallon FOB US Gulf, down US cents 39 compared to the previous month.
Acrylic input: Acrylonitrile
Acrylonitrile prices fell further in Asia this week to levels last seen in early August 2017 due to an inflow of cheaper deep-sea cargoes and prevailing sluggish demand, but the downtrend was limited by rebounding market in China and squeezed margins. The inflow of cheaper deep-sea material from the US and Europe exerted downward pressure on the Asian market as some overseas producers were destocking cargoes at the end of the year. In China, domestic spot values were range‐bound, as sellers largely followed prevalent market rates and downstream buyers picked hand to mouth volumes. However, improving upstream sentiment made suppliers keen to hike offers in spite of downstream weakness, while players were waiting for clear sign of price movement. European acrylonitrile markets were quiet and prices generally rolled over. In the US, spot export prices continued to decline as the market looked for a floor, amid depressed prices in Asia and softening global demand.
The Asian acrylonitrile Far East CFR marker declined US$50 to US$1,549-1,551 a ton, while CFR China was steady at US$1,550-1,650 a ton. In China, self-lifting values at Lianyungang port gained US$10 at US$1,700-1,715 a ton. In China, Jiangsu Sailboat posted offers at 11,800 Yuan a ton (US$1,715 a ton, up US$25) for the week. Prices in India were stable at US$1,565-1,600 a ton CFR. In Europe, spot prices rolled over at US$1,268-1,272 a ton CIF Mediterranean. In the US, spot export prices declined US$50 to US$1,470-1,480 a ton FOB USG.