Polyester input: MEG
Mono ethylene glycol markets in Asia softened after rushing high slightly early in the week, amid a modest sentiment. Spot market in China was under weak fluctuation while offers for nearby-month shipments were slightly lower. Sinopec settled its January contract lower compared with December. Meanwhile, inventories along east China increased 6% to 845 kilo ton. In Europe, the MEG market was quiet, and both truck and bulk prices generally rolled over. In the US, the MEG market continued to face headwinds in January from long supply and sluggish demand. Buying interest was slower than usual amid the winter season. Consumption was affected by lengthy PET supply amid seasonality and imports. Demand into antifreeze may receive a boost from Winter Storm Harper sweeping across the US. Export activity remained unclear since the latest trade data is unavailable because of the ongoing US government shutdown. Contracts for January declined on persistently bearish supply and demand fundamentals, with the trend expected to continue next month.
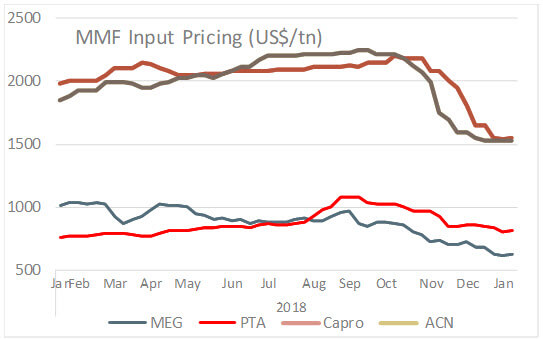
Asian spot benchmark inched up US$9 on the week, with CFR China at US$615-620 a ton while CFR South East Asia was flat at US$630-635 a ton. In China, offers for nearby-month cargoes were at US$625 a ton, while counter-offer bids were around US$620 a ton. Forward-month cargoes were discussed at US$625-630 a ton. In Europe, truck spot prices were steady at Euro670-695 a ton FCA NWE and bulk spot prices were at Euro634-675 a ton CIF NWE. In the US, January contracts were assessed at a decrease of US cents 2 from December, pegging the range at US cents 29.5-35.5 per pound FOB. Spot prices were quoted in the high-US cents 20 (US$441 a ton) for barge and in the low-US cents 30s per pound for rail and truck material.
Polyester input: PTA
Purified terephthalic acid prices were up in the Asian market on rising buy interest in the downstream polyester sector. Upstream paraxylene prices, too, firmed up slightly, providing cost support to its derivative markets. In China, futures market rebounded with momentum as offers for spots were higher than purified terephthalic acid futures. There is only one trading week left before the Spring Festival, so most of the downstream have taken vacation, and thus purified terephthalic acid market was basically quiet at weekend. Given the inventory levels in various sectors, expectation of fundamental are apparently strong after the holiday. In Europe, production issues in the purified terephthalic acid chain continued to cast shadow over the market, but weak demand and buyers’ short-term pessimistic outlook in Asia was subduing the potential impact.
Asian PTA markers, the CFR China gained US$9 on the week to US$830-832 a ton, while offers from Taiwan and Korea were up US$10 at US$850-860 a ton. In China, offers for bonded goods were around US$850-860 a ton discussions for nearby-month cargoes between US$810 and 840 a ton. Yisheng Petrochemical’s daily prices were raised US$20 to US$860 a ton, while that of Hengli Petrochemical’s were also up at US$850 a ton. In Europe, the January contract price dropped from December to Euro740-774 a ton FD NWE in the previous week. In the US, December contracts were assessed at US cents 51.05 per pound DEL USG (US$1,125 a ton).
Nylon input: Caprolactam
Caprolactam spot and contract markets remained stable in Asia on modest downstream demand and moderating upstream benzene cost. Prices of liquid materials in China remained unchanged, while flake material was cheaper and on par with liquid goods. Supply was steady while demand showed no improvement with stable run rates at polymerization units at 83% with low inventory level at less than two days’ worth. Nylon yarn makers were operating at steady rate of 73%, with inventory at 18 days’ worth. Given lukewarm benzene sentiment and modest demand, caprolactum market will hold stable trend in the coming week. In Europe, no updates were available on the progress of January caprolactum contract discussions while downstream nylon market was expecting downward pressure on their pricing on account of benzene losses.
Asian caprolactam prices remained unchanged on the week with SE and FE Asia markers stable at US$1,550-1,600 a ton. In China, spot prices for liquid goods rolled over 12,700-13,000 Yuan a ton (US$1,870-1,915 a ton) while flake goods were down to 13,000-13,600 Yuan a ton (US$1,915-2,000 a ton, down US$80). Sinopec retained its January nominations for liquid goods at 13,000 Yuan a ton (US$1,915 a ton), and Fibrant at 13,200 Yuan a ton (US$1,940 a ton). In Europe, December contracts had settled at Euro2,156-2,292 a ton FD NWE.
Acrylic input: Acrylonitrile
Acrylonitrile prices were unchanged at firm levels in Asian markets, with producers posting stable offers, while sellers’ firmed up a bit, but overall market remained quiet. Demand was slowing down ahead of the Lunar New Year break in some Asian markets. Acrylamide suppliers ran at a 70% rate with lower offers, while ABS was on a stable note, with stable prices. Acrylic yarn makers were operating at 75%, presenting continuous demand for acrylonitrile, and demand for ACN remained stable. Prices may not increase too much before the holiday as buying will subdue in the near term amid the holiday sentiment. In Europe, spot prices rolled over, while the January contract fell month-on-month on the back of lower raw material costs, good availability and a wide gap between the current spot price range. In the US, spot export prices remained unchanged following a significant decline last week.
Asian acrylonitrile Far East CFR marker remained unchanged on the week at US$1,529-1,531 a ton, while CFR China was steady at US$1,400-1,450 a ton. In China, self-lifting values at Lianyungang port were stable at US$1,735-1,765 a ton. In China, Sinopec’s January contract settlement price was 100 Yuan higher compared with December, at 11,700 Yuan a ton (US$1,720 a ton, up US$15). In Europe, prices were steady at US$1,218-1,220 a ton CIF Mediterranean, while January contract dropped Euro60 drop from December following a split settlement ranging Euro54-66 at Euro1,984.50-2,052.50 a ton FD NWE. In the US, spot export prices rolled over at US$1,250-1,420 a ton FOB USG from US$1,400-1,500 a ton the previous week.