Polyester input: MEG
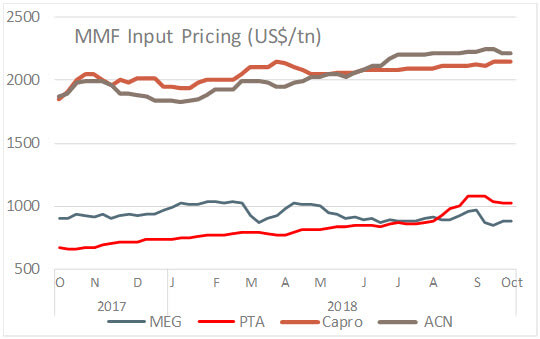
Mono ethylene glycol prices remained unchanged in Asian markets, although upstream ethylene cost fell on the week. This resulted in mono ethylene glycol margin hitting 1-month high on stable prices and lower ethylene costs. The market was characterised as balanced amid tight supply and bearish demand. Inventory along East China was estimated at around 600 kilo ton, well below the typical level of 900 kilo ton, while spot demand was limited by bearish downstream polyester demand. With week-long National Day holiday in China this week, demand is expected to pick up after the holidays due to restocking. Spot prices were flat on the week at US$885-890 a ton CFR China and at US$885-890 a ton CFR South East Asia. Sinopec had cut its October list prices to 7,500 yuan a ton (US$1,090 a ton), down US$60 from September settlement last week.
In Europe, mono ethylene glycol spot prices continued to edge down this week while the market awaited September contract to be confirmed and dual discussions alongside October are expected to take place on the sidelines of the European Petrochemical Association meeting next week. In the US, mono ethylene glycol prices were steady, but peak demand will soon begin to slow down on seasonality. Spot bulk prices were marginally down by Euro 5 on both ends, taking the range to Euro 850-865 a ton CIF NWE. Truck spot prices also edged down Euro 5 on both end, at Euro 890-905 a ton FCA NWE. Deals below Euro 880 a ton FCA were also in isolation.
In the US, MEG contracts for September rolled over at US cents 41.5-47.5 per pound FOB.
Polyester input: PTA
Purified terephthalic acid markets saw limited trading activity as China was on a week-long National day holiday. Thus, prices generally remained unchanged on the week. However, on the first trading day after the holidays, domestic market was reported to rushing higher in morning trade, but values could not be confirmed. PTA markers are notionally rolled over with CFR China at US$1,020-1,022 a ton and offer from Taiwan/Korea at US$1,030-1,032 a ton.
In Europe, the September contract was settled much higher from August, and moved alongside paraxylene September contract. Supply was constrained in Europe, and there is a planned maintenance at Indorama's Portugese site in early October. However, shutdowns in downstream PET in September/October, and ending of high bottling season, market remained more balanced. In the US, September contracts were assessed higher, tracking spike in paraxylene contracts. Production remained limited as Indorama has planned maintenance on its 600 kilo ton PTA plant in Montreal, Canada from 12-28 October. Demand is likely to wane as peak bottling season has concluded and markets should be more balanced with supply levels going into winter months. September contract was raised by Euro 141 from August, to reach Euro 904-938 a ton FD NWE.
In the US, September PTA prices were assessed at US cents 60.10 per pound DEL, up by US cents 7.04 and following US cents 2.85 cents/lb increase in August.
Nylon input: Caprolactam
Caprolactam prices remained unchanged Asian markets during the weeklong holiday while benzene prices surged on strong crude oil. During the week, market players mainly chose to wait and see, with a few sellers pushing prices higher. Prices are expected to rise after the holidays in China and Taiwan demand will firm up amid supply shortages due to maintenance in the region. In Europe, caprolactam October pricing expectations were lower due to benzene feedstock decreases, coupled with uncertainty surrounding automotive demand ahead of the upcoming European Petrochemical Association. Depending on how demand develops in nylon 6 market, negotiations for caprolactam could be tricky as non-integrated nylon players are looking for some pricing relief because of lower benzene costs. September contracts had settled at Euro2,272-2,433 a ton FD NWE rolling over from August.
Asian caprolactam markers rolled over this week with SE and FE Asia at US$2,150-2,200 a ton. In China, spot prices for liquid goods softened to 17,800-18,500 yuan a ton (US$2,590-2,690 a ton) while flake goods were at 18,100 yuan a ton (US$2,630 a ton). Taiwan's China Petrochemical Development Corporation had settled its October contract price at US$2,240 a ton CFR NE Asia, up US$70 from September last week.
In the US, cyclohexane contract, a precursor to caprolactam, for October softened on decreases in benzene market. Contract settled at US cents 297 a gallon FOB US Gulf, down US cents 9 compared to the previous month.
Acrylic input: Acrylonitrile
Asian acrylonitrile markers rolled over on the week with Far East CFR at US$2,219-2,221 a ton while CFR China was flat at US$2,200-2,230 a ton. In China, self-lifting values at Lianyungang port rolled over at US$2,760-2,775 a ton. In Europe, acrylonitrile spot activity was limited, and prices rolled at US$2,048-2,052 a ton CIF Mediterranean after September contract prices were settled Euro 34 up at Euro 2,133-2,201 a ton FD NWE.
In the US, acrylonitrile spot export prices were flat at US$2,110-2,130 a ton FOB USG as global supply remained tight.