Polyester input: MEG
Mono ethylene glycol discussions in Asia were muted as the market adopted a more cautious stance on opposing factors. While higher inventory levels at China main ports have reduced the buying appetite, further gains in crude oil prices and an uptick in polyester sales led to a positive note among players. Inventory levels rose 8.4% after delayed shipments arrived, to around 732 kilo tons. MEGlobal’s February contract price was down as spot prices lost ground in January amid bearish sentiment over China’s economy. In Europe, MEG truck prices faced downward pressure as competitive offers emerged in the market, despite increased activity after the festive break. Truck market participants returned but demand was not as high as some sellers expected. Temperatures starting dropping and there was hope for uptick in demand from the antifreeze sector. Prices in the south of Europe were higher compared to northern Europe. January contract was confirmed at a decrease exerting further downward pressure on spot pricing.
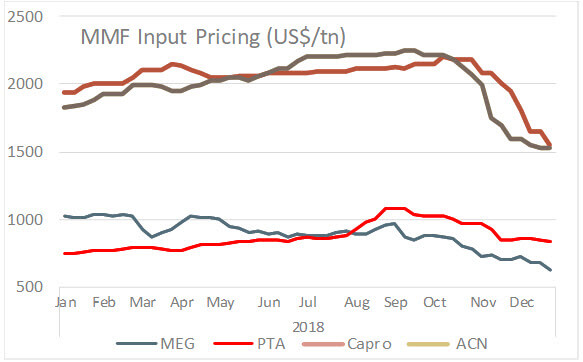
Asian spot benchmark edged down US$2 on the week, with CFR China at US$618-623 a ton while CFR South East Asia inched up US$5 to US$625-635 a ton. In China, offers for nearby-month cargoes were at US$625 a ton and bids were around US$620 a ton with discussion stalemated. MEGlobal announced its February contract price at US$810 a ton CFR Asia, down US$90 from January nomination. In Europe, truck spot prices were Euro20 down at both ends, bringing prices to Euro695-720 a ton FCA NEW, while bulk spot prices edged down Euro5 on both ends to Euro675-695 a ton CIF NWE. January contract was fully confirmed at Euro790 a ton, down Euro35 from December. In US, December contracts were assessed at US cents 31.50-37.50 per pound FOB.
Polyester input: PTA
Purified terephthalic acid prices in Asian markets gained this week but margins were under pressure on surging feedstock paraxylene cost. Paraxylene prices were on the rise, as a result of rebound in upstream energy, and an optimistic global macroeconomic market outlook. Purified terephthalic acid supply is likely to remain largely balanced to tight due to limited capacity expansion, while demand is expected to continue growing. China will remain the key demand growth driver for Asia, followed by India. Uncertainties in global macroeconomic environment, due to ongoing US-China trade war, could cap demand growth. No reports were available from European and US purified terephthalic acid markets this week after their December contract prices were settled last week and in late December.
Asian PTA markers, the CFR China gained US$20 on the week to US$805-807 a ton while offer from Taiwan/Korea was up US$10 at US$810-830 a ton. In China, offers for bonded goods were around US$820 a ton discussions for nearby-month cargoes between US$780-820 a ton. Yisheng Petrochemical’s daily prices were raised US$10 to US$830 a ton while that of Hengli Petrochemical’s were up at US$830 a ton. In Europe, December contract price was pegged at Euro770-804 a ton FD NWE. In the US, December contracts were assessed at US cents 51.05 per pound DEL USG (US$1,125 a ton).
Nylon input: Caprolactam
Caprolactam market sentiment in Asia improved as benzene market rebounded pushing prices back to two weeks ago levels. In China, prices of liquid goods rebounded while those of flake material surged sharply. In contract, both Sinopec and Fibrant rolled over their January contract nominations for liquid goods. Demand was slowly rising as run rates of polymerization units rose to 81% with inventory level at three days’ worth. Yarn makers were operating at stable rate. As benzene took a small rally, and caprolactam demand picked up a bit, and prices are likely to bottom out in coming weeks. In Europe, talks for January contract were still in initial stages as precursor cyclohexane market was tightened this week due to delayed imports. Reports indicated delayed vessels are expected to arrive in H2 January, after which the market would become balanced. Demand for caprolactam has increased as expected following the New Year holidays.
Asian caprolactam prices recovered US$10-20 on the week with SE and FE Asia markers back to US$1,550-1,600 a ton. In China, spot prices for liquid goods surged to 12,600-12,700 Yuan a ton (US$1,855-1,870 a ton, up US$60) while flake goods were up at 13,500-13,600 Yuan a ton (US$1,990-2,000 a ton, up US$135). Sinopec retained its January nominations for liquid goods at 12,800 Yuan a ton (US$1,885 a ton), and Fibrant at 13,000 Yuan a ton (US$1,915 a ton). In Europe, December contracts had settled at Euro2,156-2,292 a ton FD NWE. In the US, December cyclohexane settled at US cents 212 per gallon FOB US Gulf.
Acrylic input: Acrylonitrile
Acrylonitrile prices moved sideways in Asian markets this week as upstream propylene saw a strong rebound. No major issue was reported in the market, as players were focused on post-holiday movement. Currently, demand was stable as acrylamide suppliers ran at modest rate and pries still flat. The ABS market was in stable note, while acrylic yarn makers raised their run rate pushing up demand for acrylonitrile. Prices are likely to fluctuate in 2019 given the anticipated ample supply, weak downstream demand and slowing global economic growth. European acrylonitrile markets were still quiet with no reports emerging this week. In the US, spot export prices fell amid sluggish demand stemming from limited demand in Asian acrylic fibres and acrylonitrile-butadiene-styrene markets. Weaker domestic buying interest pressured spot export prices down, while producers focused on strong contractual demand amid constrained supply in the domestic market.
Asian acrylonitrile Far East CFR marker rolled over at US$1,529-1,531 a ton while CFR China was steady at US$1,400-1,450 a ton. In China, self-lifting values at Lianyungang port were steady at US$1,725-1,740 a ton. In China, PetroChina Jilin increased its offer prices by 250 Yuan to 11,150 Yuan a ton (US$1,640 a ton, up US$36.5) ex-warehouse. Prices in India were stable at US$1,450-1,450 a ton CFR. In Europe, spot prices rolled over at US$1,218-1,220 a ton CIF Mediterranean. In the US, spot export prices declined US$50 to US$1,420-1,430 a ton FOB USG.