Polyester input: MEG
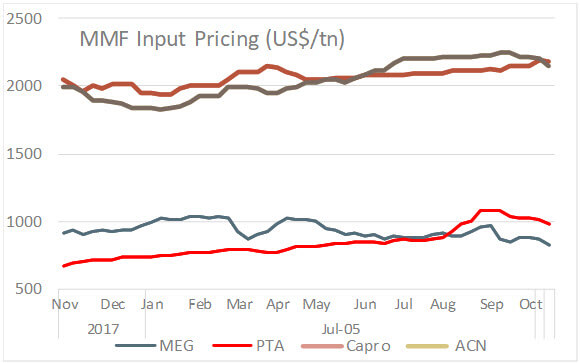
Mono ethylene glycol prices in Asia weakened amid a bearish market sentiment after recent losses in crude oil values and lackluster sales in downstream polyester industry. Downstream polyester prices also declined as production was ramped up amid lukewarm demand. Losses in crude oil prices further exerted downward pressure on polyester and MEG prices. Meanwhile, inventories along east China increased 4% week-on-week to 604 kilo ton on increased arrival of imported cargoes. Spot prices plunged US$60 week-on-week with CFR China at US$793-798 a ton and CFR South East Asia at US$800-810 a ton.
In Europe, players in MEG market were awaiting October contract settlement, as talks continued. A dual agreement alongside November discussions is expected. Bulk spot prices slipped further this week on good import supply while truck prices were stable to soft. Bulk range was assessed at a Euro 30 decrease on the lower end and 34 at the high, bringing prices to Euro 800-806 a ton CIF NWE. Truck spot prices softened Euro 5 a ton to Euro 850-870 a ton FCA NWE.
In the US, MEG October contracts were settled down last week at US cents 40.5-46.5 per pound FOB, while ethylene oxide contract prices for October fell 3.3% this week on the back of a decrease in contract settlement for ethylene.
Polyester input: PTA
Purified terephthalic acid prices dropped in Asian markets, while futures market in China retreated significantly once again. Support from the upstream paraxylene market turned weaker while processing margin stayed stable with a likelihood to recover further. The average plant run rate in China dropped to 73% last week due to the plant turnarounds at Yisheng Petrochemical and BP Zhuhai Petrochemical. Asian PTA markers CFR China fell US$40 on the week at US$920-922 a ton, while offers from Taiwan/Korea were stable at US$970-990 a ton. In China, offers for bonded goods edged down US$30 to US$970-1,000 a ton, and discussions for nearby-month cargoes were around US$900 a ton.
In Europe, October contract decreased moving alongside lower paraxylene October contract price. Meanwhile spot remained unchanged. October contract price was down Euro 15 at Euro889-923 a ton FD NWE.
In the US, October contracts were assessed at a rollover assessed at US cents 60.10 per pound DEL USG, tracking flat contract for paraxylene.
Nylon input: Caprolactam
Caprolactum markets in Asia were quiet this week amid uncertainty and volatile prices in domestic China. Downstream nylon chips prices also softened in the week as sellers were under pressure from falling feedstock prices the previous week, and the overall market sentiment was poor. Major caprolactam makers released their offers for November shipments slightly higher than October settlements. Asian markers were stable to moderate, with SE and FE Asia markers flat at US$2,180-2,220 a ton. In China, spot prices for liquid goods were at 16,200-16,500 Yuan a ton (US$2,335-2,380 a ton) while flake goods were at 16,500 Yuan a ton (US$2,380 a ton). Sinopec nominated November contract price at 17,500 a ton (US$2,520 a ton, up US$20 from October settlement).
In Europe, October caprolactam contract discussions were concluded with drops due to lower October benzene costs. Talks were extensive with suppliers originally aiming for pricing stability at the start of the month, despite lower feedstock costs. There were worries about weaker automotive demand including the nylon 6 market, along with a general concern for the future due to macroeconomic and political uncertainty. October contract prices fell Euro8-16, bringing prices in the range of Euro2,264-2,417 a ton FD NWE. The upstream Cyclohexane contract for November softened to Euro858 a ton ex-works.
Acrylic input: Acrylonitrile
Acrylonitrile markets in Asia continued their downtrend on falling feedstock prices and weak downstream demand. In China, domestic prices dropped by 17% on the week due to weak market sentiment. Buying appetites were largely dampened due to consecutive drops in the spot market and sluggish demand from the acrylic fibre sector. Major producers also dropped their list and contract prices citing soft demand from acrylic fibre makers. The Far East CFR marker fell US$50 to US$2,129-2,131 a ton, while CFR China was steady at US$2,150-2,220 a ton. In China, self-lifting values at Lianyungang port fell US$105 to US$2,505-2,520 a ton.
In Europe, acrylonitrile prices declined amid downstream production cuts in the region and economic slowdown in China. Acrylic fibre producers in the region have reduced production, thus reducing overall demand for acrylonirtrile by about 10-12 kilo ton. Spot prices dropped US$100 to US$1,898-1,902 a ton CIF Mediterranean.
In the US, export acrylonitrile prices fell in line with declining values in Asia and Europe. A lack of offers for spot was limited by severe drop in prices as producers in the region continued to focus on rebuilding inventories for 2019 buying year. Acrylonitrile-butadiene-styrene and acrylic fibre demand continued to soften amid weak production margins. Spot export prices were down US$25 at US$2,085-2,095 a ton FOB USG. October domestic contracts settled higher at US cents 80.90-84.90 per pound DEL from US cents 80.48-84.48 per pound DEL in the previous month.