Polyester input: PTA
Purified terephthalic acid prices moderated in Asian markets despite feedstock paraxylene trending up on the week. In China, the futures market fluctuated due to spot offers, which were at a buyout level and suppliers mainly focused on offloading cargoes. In China, the average plant operating rate dropped to 83% this week from 88% clocked last week. Xiang Lu Petrochemical’s plant, which has three lines, was shut this week while Sinopec Luoyang’s unit remained offline. In Taiwan, Formosa Chemicals Mailiao was also shut for scheduled maintenance for 20-25 days. Affected by negative factors, players averted risk in operations when the market fluctuated widely. On the other hand, there was a conflict between spot prices and polyester margins, thus the focus will be on destocking in the terminal market. If the situation does not improve, there will be a high probability that the gap between the two will narrow.
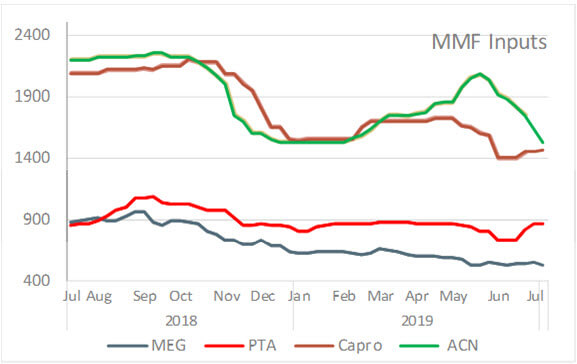
Asian marker, the CFR China, slumped US$30 on the week to US$760-762 a ton, while offers from Taiwan and Korea were at US$860-870 a ton. Offers for bonded goods on one-day trip stayed at US$860 a ton. In Europe, June contract price was assessed at Euro671-705 a ton FD NWE. In the US, June contracts were at US cents 47.45 per pound (US$1,046 a ton) DEL, losing US cents 3.25 per pound from May.
Polyester input: MEG
Mono ethylene glycol markets in Asia fluctuated in weakness and saw a limit down under the influence of poor macro-economic sentiment and retreating downstream polyester market. As a result, prices fell week on week. Meanwhile, inventories along east China were largely stable at 1,150 kilo ton as expected, because majority of cargo arrivals were on weekend. MEGlobal nominated its August unchanged from its July, citing spot prices were under pressure on concerns of possible downstream polyester production cuts while supply is expected to increase in H2 July. In Europe, mono ethylene glycol spot prices continued to slump as inventory levels remain high in ARA region and there were regular volumes entering from the US. Both bulk and truck spot prices were assessed stable-to-soft this week. In the US, the July price was steady amid length in supply and soft demand. Demand for MEG in polyethylene terephthalate was sluggish, with downstream supply ample. A seasonal pick-up appears to be limited this year as economic headwinds cloud the demand outlook.
Asian benchmark, the CFR China fell US$21 on the week to US$520-525 a ton while the CFR South East Asia values were down to US$530-535 a ton. Offers for nearby-month cargoes were at US$528 a ton and bids around US$525 a ton. Offers for forward-month cargoes were US$3-5 higher than that for nearby-month cargoes. MEGlobal nominated its August Asian contract price at US$710 ton CFR Asia, unchanged from July nomination. In Europe, bulk spot prices were assessed Euro10-15 softer at Euro495-505 a ton CIF NWE, while truck spot prices were heard at Euro505-515 a ton FCA NWE. In the US, June contracts were assessed at US cents 22.50-28.50 per pound (US$496-628 a ton) FOB USG while spot prices were quoted in the low-US cents 20s per pound (US$441 a ton) for barge material and in mid-US cents 20s per pound for rail/truck material.
Nylon input: Caprolactam
Caprolactam markets in Asia derived strength from rising upstream benzene cost and prices climbed in line. Both spot and contract prices were up and buyers followed up somewhat amid tight supply. In China, prices of liquid caprolactam were up 1% on the week while of flake material rolled over. In contracts, Sinopec and Fibrant lifted their July nomination for liquid goods. Demand was almost stagnant as run rates in downstream polymerization units were steady at 71%, while yarn makers ran at 84%. With benzene market rebounding and downstream demand following up somewhat, caprolactam prices are likely to nudge higher in the short-term.
Asian caprolactam prices were up US$10 at US$1,460-1,500 a ton CFR SE and FE Asia. In China, spot liquid goods prices moved up to 12,500-12,600 Yuan a ton (US$1,820-1,835 a ton, up US$15) while flake goods were flat at 13,000-13,200 Yuan a ton (US$1,890-1,920 a ton). Sinopec lifted its July contract price to 12,600 Yuan a ton (US$1,835 a ton) and Fibrant to 12,700 Yuan a ton (US$1,850 a ton). In Europe, June contract prices were settled at Euro2,101-2,225 a ton FD NWE while, cyclohexane contract for July were raised to Euro798 a ton ex-works NWE. In the US, cyclohexane July contracts were at US cents 272 a gallon FOB USG.
Acrylic input: Acrylonitrile
Acrylonitrile prices in Asian markets continued to trend down and apparently levelled off. In China, offers plunged but seeing sparse trading activities, prices appeared to touch bottom, and participants still held a bearish outlook. Shanghai SECCO dropped its weekly price, citing the sharp decline in domestic spot prices on the back of sluggish acrylic fibre demand. In Europe, acrylonitrile prices did not move this week on the back of slower demand and gradually improving supply. INEOS Nitriles lifted the force majeure on supply from its unit in Germany, although full volumes were supplied throughout June. Allocation rates remain in place at its UK plant in July, and the declaration will not be lifted until normal inventory levels are resumed. In the US, spot export prices extended the downtrend amid mixed demand and expectations that INEOS Nitriles will restart its US Green Lake plant this month. Falling raw material costs and lower prices in Asia also added to the downward pressure.
Asian acrylonitrile marker, the Far East CFR plunged US$110 week on week to US$1,529-1,531 a ton while CFR China declined US$100 to US$1,550-1,600 ton. In China, self-lifting values at Lianyungang port fell US$70 to US$1,590-1,600 a ton. Shanghai SECCO dropped its weekly price by 800 Yuan to 11,500 Yuan a ton (US$1,669 a ton, down US$115) ex-tank. In India, prices were down US$50 to US$1,600-1,650 a ton CFR. In Europe, spot prices remained unchanged on the week to US$1,718-1,722 a ton CIF Mediterranean. In the US, spot export prices decreased US$55 to US$1,760-1,770 a ton FOB US Gulf.