Polyester input: MEG
Mono ethylene glycol prices declined in Asian markets on the week, despite inching up at the weekend due to increased offtake volumes and in line with an increase in crude values. Demand outlook was weak as some downstream polyester producers will cut operation rate ahead of the Lunar New Year holidays, while supply was ample as production hit a record high in December in China. Meanwhile, inventories in east China were up 8.7% to 796 kilo tons on the week. In Europe, spot prices continued to tumble on flat demand and downcast mood prevailing in the market. Demand was hard to pick as expected as the peak antifreeze season was approaching the end. Bulk prices dropped significantly this week while truck prices were also once again under pressure throughout the week, mainly due to the bearish sentiment caused by the losses seen in the bulk market. In the US, the mono ethylene glycol market continued to face headwinds from long supply and sluggish demand. Buying interest was slower than usual during the winter season.
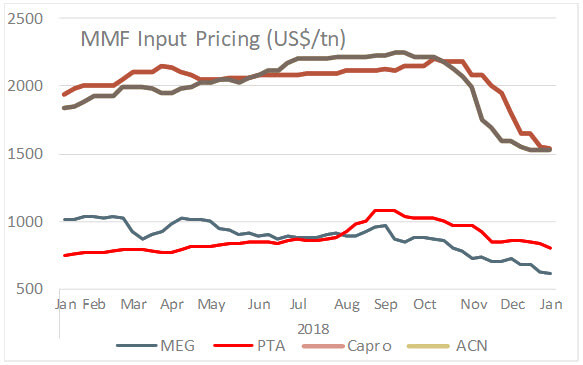
The Asian spot benchmark fell US$12 on the week, with CFR China at US$606-611 a ton, while CFR South East Asia inched up US$5 to US$630-635 a ton. In China, offers for nearby-month cargoes were at US$610 a ton and bids were slightly below with discussion stalemated. In Europe, truck spot prices decreased Euro25 at both ends of the range, pegging prices at Euro670-695 a ton FCA NWE. Bulk spot prices were down Euro41 at the low end and Euro20 at the high, taking the range to Euro634-675 a ton CIF NWE. In the US, spot prices are quoted in the high-US cents 20 (US$441 a ton) for barge and in the low-US cents 30s per pound for rail/truck material. December contract price was settled at US cents 31.5-37.5 per pound FOB USG.
Polyester input: PTA
Purified terephthalic acid prices gained in Asian markets on rising offtake from downstream polyester makers ahead of the Lunar New Year holidays. However, the rise was capped by low interest to build long positions as terminal demand remained weak for initial few weeks after the holidays. The current condition is that prices will tend to rise easily and have difficulty to go down in the near future. Weekend saw futures in China carrying on strong momentum while spots were traded several times at fixed values. In Europe, January purified terephthalic acid contract prices dropped for the fourth consecutive month, following the decline in upstream paraxylene contract for the month. In the US, purified terephthalic acid market was quiet after the December contract was settled earlier this month.
Asian PTA markers, the CFR China rose US$16 on the week to US$821-823 a ton, while offers from Taiwan/Korea were up US$30 at US$840-850 a ton. In China, offers for bonded goods were around US$840 a ton and discussions for nearby-month cargoes between US$800 and US$820 a ton. Yisheng Petrochemical’s daily prices were raised US$10 to US$840 a ton, while that of Hengli Petrochemical were also up at US$840 a ton. In Europe, the January contract price dropped Euro30 from December to Euro740-774 a ton FD NWE. In the US, December contracts were assessed at US cents 51.05 per pound DEL USG (US$1,125 a ton).
Nylon input: Caprolactam
Caprolactam spot market held stable run this week on moderate demand and steady benzene prices. In China, prices for domestic liquid goods rebounded while those for flaked goods rolled over. In contract, both Sinopec and Fibrant raised their January contract nominations for liquid goods by 1.5% over the week. Supply was steady while demand showed improvement with run rates of polymerization units rising to 83% with low inventory level at two days’ worth. Nylon yarn makers were operating at a steady rate of 73%, with inventory at 19 days’ worth. In Europe, no reports were available on the progress of January contract discussions. Overall, as benzene market was range bound and demand picking up a bit, caprolactam markets are likely to remain stable in coming week.
Asian caprolactam prices rolled over on the week, with SE and FE Asia markers at US$1,550-1,600 a ton. In China, spot prices for liquid goods rebounded to 12,700-13,000 Yuan a ton (US$1,875-1,920 a ton, up US$20), while flake goods were steady at 13,500-13,600 Yuan a ton (US$1,995-2,005 a ton). Sinopec raised its January nominations for liquid goods to 13,000 Yuan a ton (US$1,920 a ton, up US$35 from last week), and Fibrant to 13,200 Yuan a ton (US$1,950 a ton, also up US$35). In Europe, December contracts had settled at Euro2,156-2,292 a ton FD NWE.
Acrylic input: Acrylonitrile
Acrylonitrile prices in Asia were apparently near bottom due to squeezed margins as they rolled over this week, with some inching up seen in China. Trading activities were winding up in China, amid a silent market, and all deliveries will be completed in next week. Thus, an immediate uptrend will now depend on downstream demand. In Europe, acrylonitrile spot prices stopped falling after dropping for the past two consecutive weeks on low demand. Export demand was also sluggish due to limited buying from Asian acrylic fibres and acrylonitrile-butadiene-styrene markets. In the US, spot export acrylonitrile prices declined sharply as the market approached a floor amid a lack of significant liquidity in recent months. Re-stocking efforts in Asia, ahead of the Lunar New Year holiday also pressured price discussions down in US as the region looks to build inventory before demand picks up later in Q1. Despite healthy domestic demand, global demand was slower than expected in January.
The Asian acrylonitrile Far East CFR marker remained flat over the week at US$1,529-1,531 a ton, while CFR China was steady at US$1,400-1,450 a ton. In China, self-lifting values at Lianyungang port were up US$20 at US$1,745-1,770 a ton. In China, PetroChina Jilin offer prices were at 11,150 Yuan a ton (US$1,640 a ton5) ex-warehouse. Prices in India were stable at US$1,450-1,450 a ton CFR. In Europe, spot prices rolled over at US$1,218-1,220 a ton CIF Mediterranean. In the US, spot export prices fell to US$1,250-1,420 a ton FOB USG from US$1,400-1,500 a ton the previous week.