India, one of the biggest textile producers in the world, has become the world’s largest cotton fibre producer with last season’s output of 36.5 million bales. The country also remains the largest importer and consumer of the fibre. The FAO-OECD outlook for cotton projects that India will remain the world’s largest cotton producer over the next 10 years.
India is now on the cusp of opportunity with its cotton, in view of the twists and turns in the global cotton scenario, and especially with the major decline in cotton stocks in China due to the liquidation of government-controlled cotton reserves in the past few years. Also, the impending sentiments created by the ongoing US-China trade war will substantially reduce the inflow of US cottons into its largest consumer: China.
However, overall there is good news for global cotton demand as the supplies will get tightened for the current 2018-19 season. The world’s cotton stocks, especially due to China, will get reduced to levels that were last seen five years ago. Also, the global cotton production of approximately 26 million tons is set to fall short of the estimated world consumption demand of 27.6 million tons.
Like in many commodities such as oil, steel and coal, the ‘China factor’ is the mover and shaker in the global cotton market too. This is mainly due to a drastic decline of nearly 6.6 million tons in its cotton stocks. This indicates that China will return to the market as the largest net importer/buyer of cotton. With the ongoing trade war between China and the US, and China having imposed a punitive duty/tariff of 25% on cotton originating from the US, the door of opportunity in the cotton industry is certainly open to players other than the US and especially to India as largest producer of cotton. Brazil is also set to benefit with increased imports of the fibre by China.
India’s cotton scenario 2018-19
Though India will stay the world’s largest producer, its cotton output is likely to fall 4.5-6%, to the level of 34.80 million bales compared to last season’s output of 36.5 million bales. As per the CAI association, the decline in output has been due to low rainfall and pest bollworm attacks in some cotton growing states. The downfall in the output will be impact cotton and yarn exports amid the enhanced demand predicted to come in from China. The biggest drop in output will be seen in the biggest cotton producing state of Gujarat where there has been average 25-28% shortfall in the rain. This will lead to a drop of 15% in Gujarat’s cotton production.
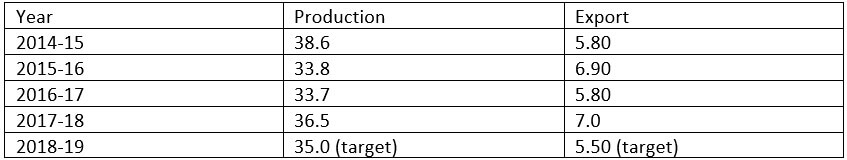
Vietnam, China, Bangladesh and Pakistan are the major buyers of Indian cotton. The demand for Indian cotton from China is robust in the aftermath of China’s punitive 25% import duty imposed on US cotton. However, due to less production in a few Indian states, the exports are likely to reduce and also, the imports to increase.
Opportunity for India versus Brazil
Brazil is likely to be the key beneficiary of the ongoing cotton trade/export trade war between the US and China. Its targeting to increase its cotton experts by nearly 20% to reach 1.2 million tons by the end of the 2018-19 season. This may make India the world’s second-largest exporter after the US.
So, is there an opportunity for Indian cotton in the global cotton markets? As per the Government Ministry of Agriculture, the total planted area remains nearly the same as the last few years.
Also, the private players in the cotton domain place the estimates at a higher level/target of 35 million bales. In this other scenario, India will have a surplus of around six million bales in its overall cotton balance in relation to targets for export and imports. Indian cotton exports will also be supported by the deprecation of the Indian Rupee, which has depreciated nearly 14% compared to the the dollar in the last year compared to other cotton exporters.
This will provide a price competitive edge to cotton exports from India and thus needs to be supported by the Indian government and industry to maximise exports, especially to nearby markets such as Bangladesh and China. India’s Commerce Ministry is actively supporting all initiatives to maximise the exports of cotton to help India close its trade gap/balance with China.
In conclusion, demand trends for domestic cotton yarn remain upbeat and the enhancement in export demand, especially from China, looks promising for the capacity utilisation and profitability of the yarn spinning mills in the wake of depreciating Indian Rupee. Thus, this will help to absorb any surges in the raw material/cotton fibre prices in the second part of the season. In this scenario, India is set to record strong growth in the cotton yarn exports during 2018-19 and, will be able to face any competition from an upbeat Brazil.