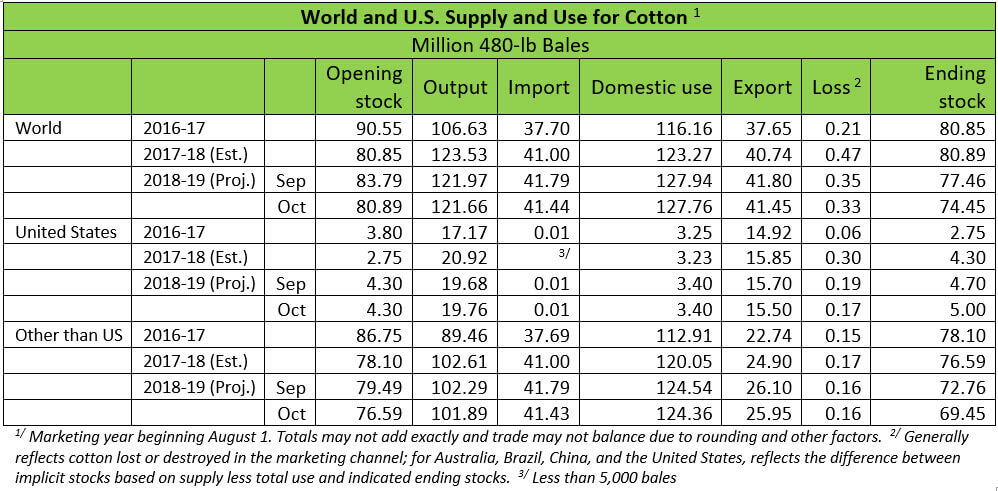
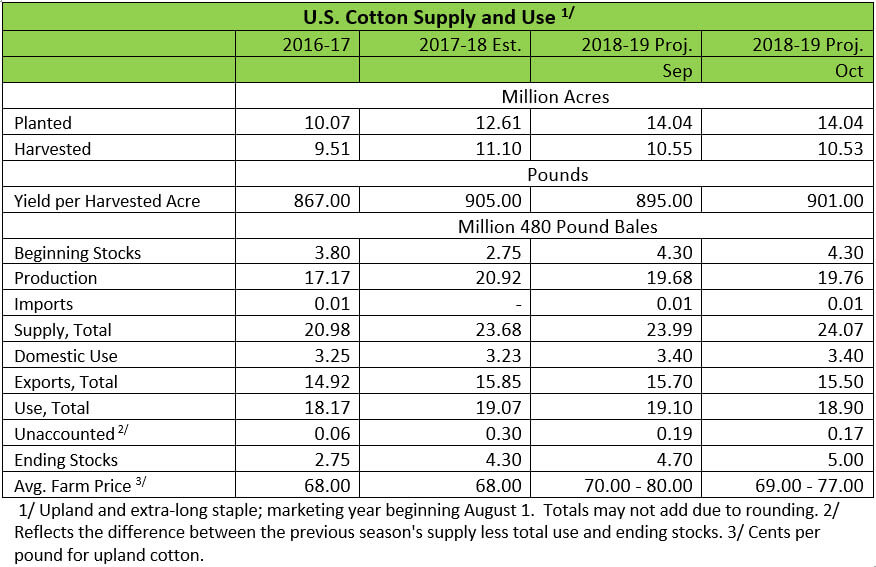
The WASDE report of October 2018 on US cotton supply and demand estimates show higher ending stocks, based on slightly larger output and lower exports compared to the estimates of last month. Production is raised 81,000 bales, with higher production in Texas and Georgia largely offset by lower production in the Carolinas.
US domestic mill use is unchanged from last month, but the export forecast is reduced 200,000 bales to 15.5 million, due to reduced world trade and consumption. Ending stocks are forecast at 5 million bales, and the resulting stocks-to-use ratio of 26% is slightly higher than the previous month’s forecast, and the highest since 2015-16.
Farm price forecast range for the marketing year average is US cents 69-77 per pound; the midpoint of US cents 73 is down US cents 2 from the previous month’s projection.
Production forecasts are lowered for Australia and raised for Greece and the US. Consumption and imports are lowered for Turkey.
Global ending stocks forecast for 2018-19 is lowered 4% this month as lower production and sharply lower beginning stocks offset marginally smaller consumption. Stocks are lowered mainly in India, as revisions are made to production, consumption, and loss over 2002-03 and 2013-14 to better reflect Indian government data (consumption) and the impact of shifting producers’ marketing patterns.
Global beginning stocks are lowered 2.9 million bales and ending stocks are lowered 3.0 million bales. Ending stocks in 2018-19 are down 6.4 million bales from last year, largely reflecting an expected 8.2-million-bale decline in China.