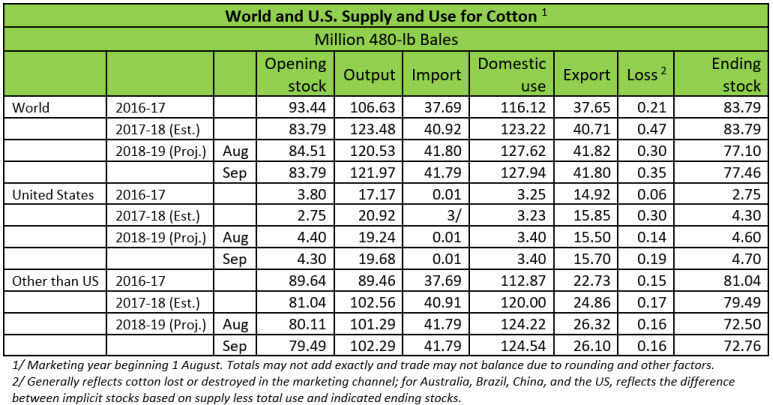
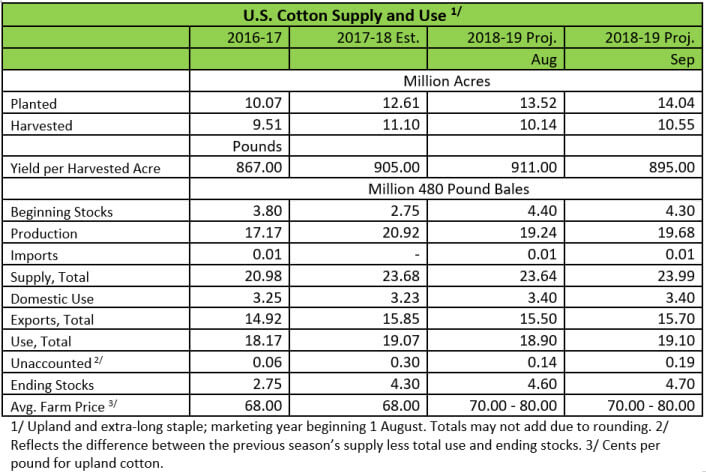
The World Agricultural Supply and Demand Estimates (WASDE) report of September 2018, has estimated US cotton production, exports and ending stocks will be larger in 2018-19 relative to its numbers in August.
Production is raised 447,000 bales, with increases in the Southwest, Delta, and Southeast. Beginning stocks are revised 100,000 bales lower based on indicated stocks as of 31 July 2018, while domestic mill use is reduced slightly in 2017-18 based on recent activity.
The 2018-19 export forecast is raised 200,000 bales. Ending stocks are now projected higher at 4.7 million bales, or 25% of total use. The forecast range for the marketing-year average farm price is unchanged at US cents 70-80 cents per pound.
For the world, larger 2018-19 cotton production mostly offsets lower beginning stocks, and world ending stocks are only slightly higher this month.
Beginning stocks are reduced for India and the US due to revisions in 2017-18 estimates.
Production is raised for China, Brazil, and the US but is lowered for Australia.
Global consumption is increased 300,000 bales due to higher expected use in India, and trade is unchanged.
World ending stocks are projected about 400,000 bales higher this month, at 77.5 million bales, equivalent to 61% of world consumption. If realized, this stocks/use ratio would be its lowest in eight years, but higher than in virtually every other year before 2010-11.